
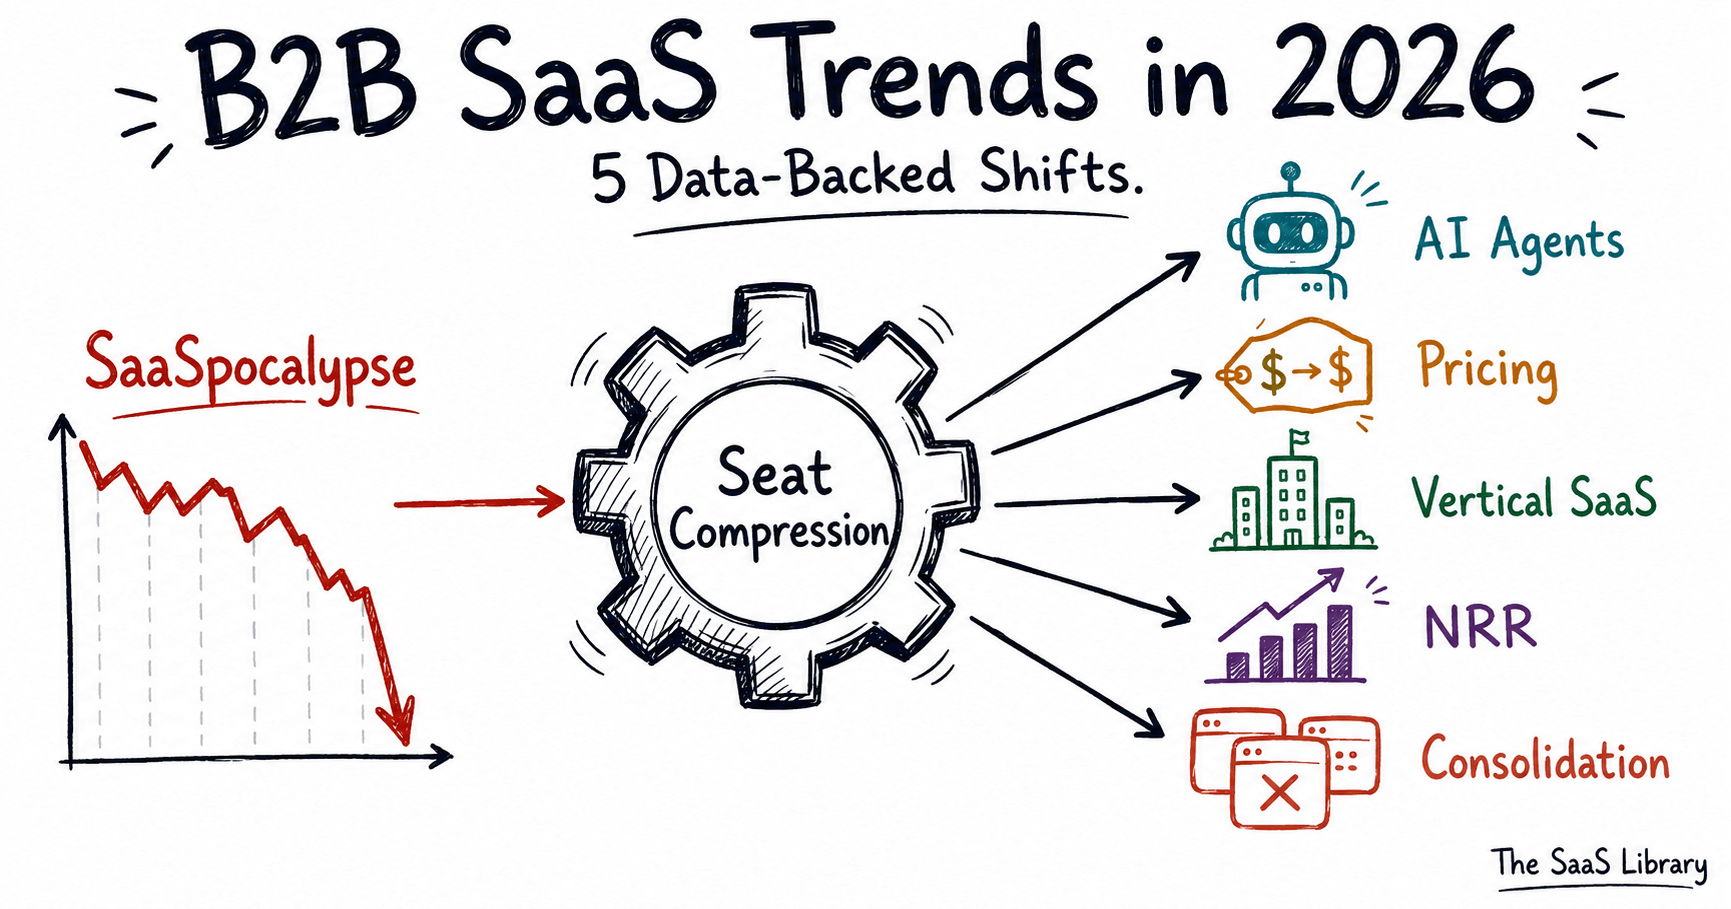
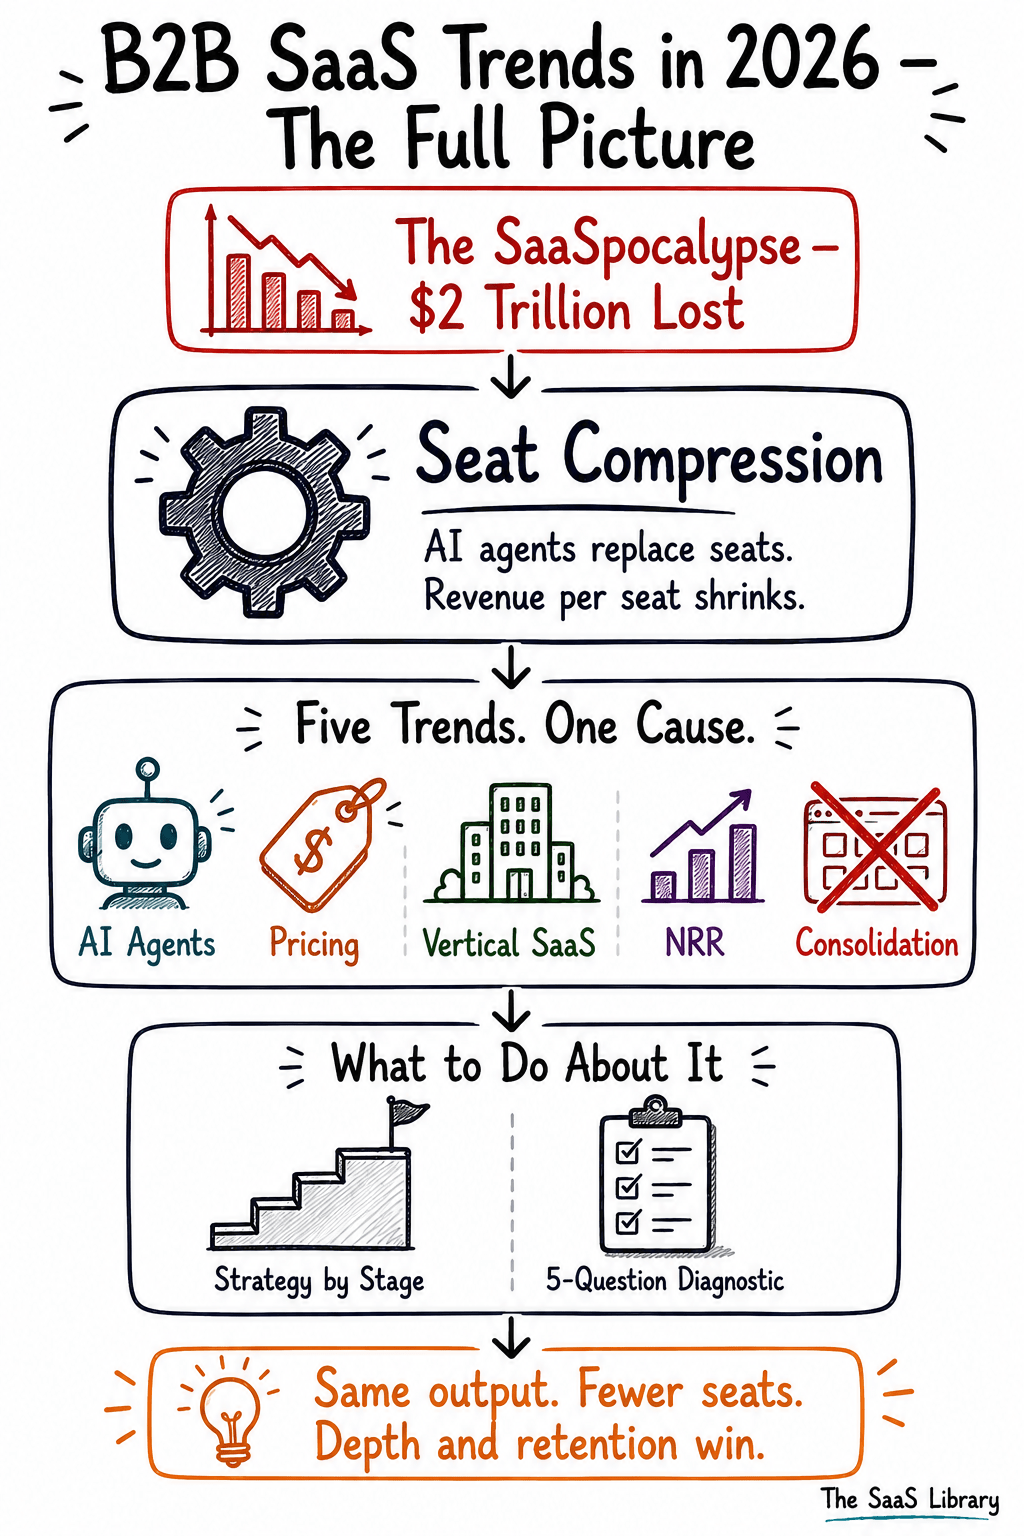
In January 2026, software stocks lost close to $2 trillion in market value in eight weeks. That wasn’t a correction — it was the market pricing in one structural shift: AI agents doing work software used to sell as seats.
What Caused the 2026 B2B SaaS Market Selloff?
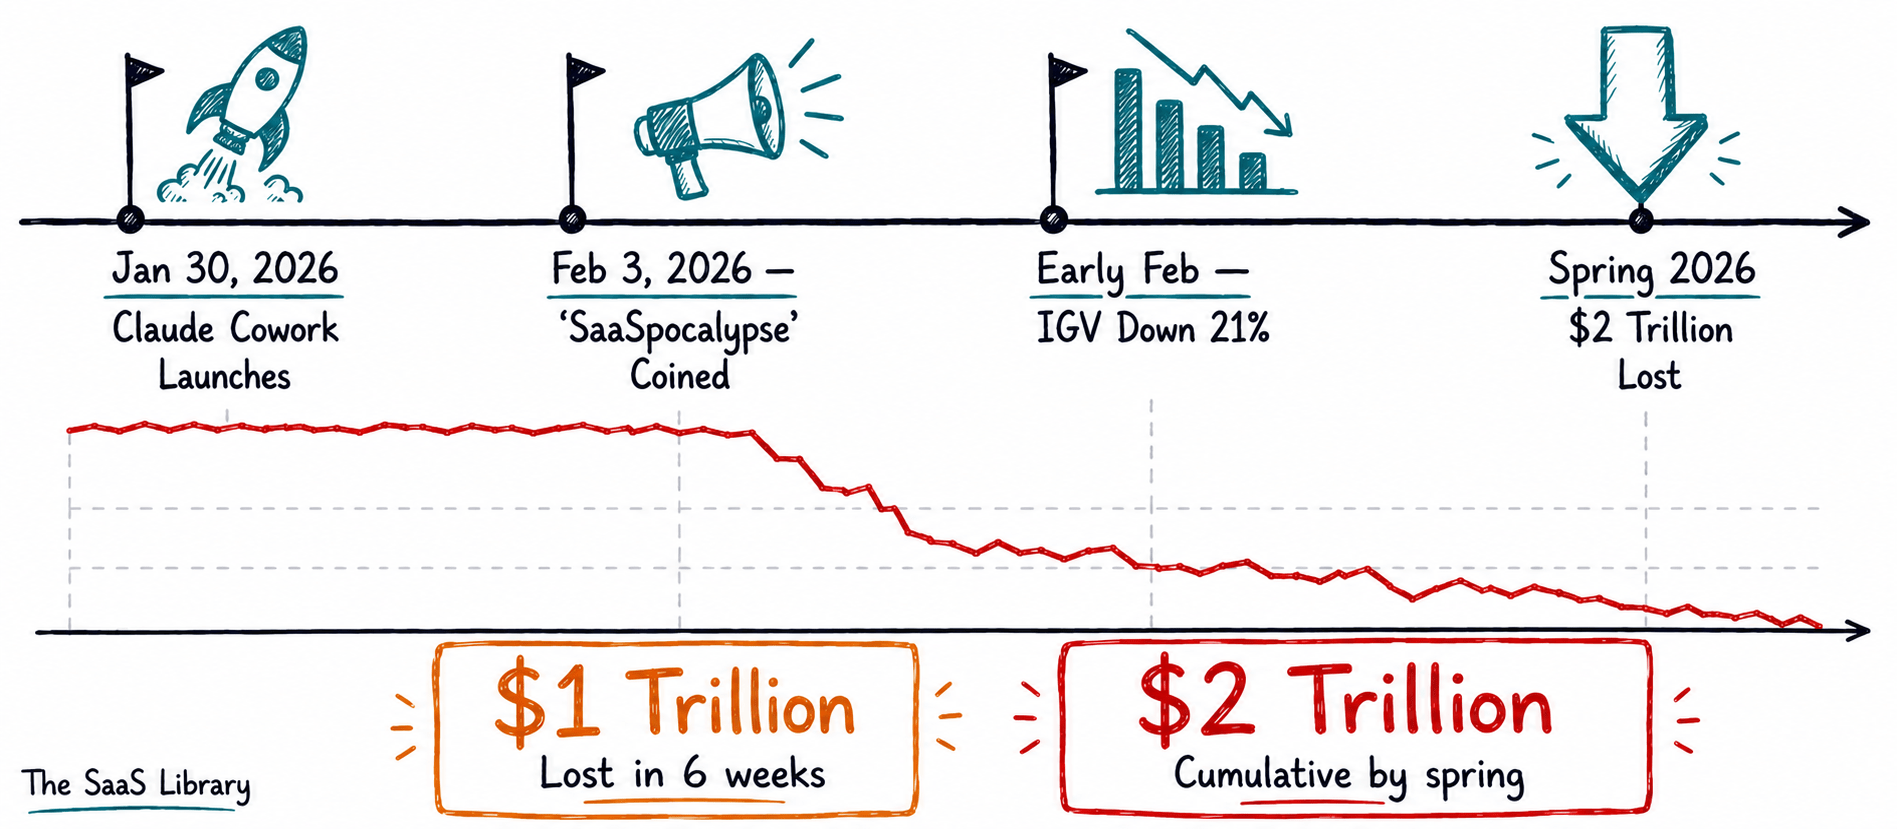
The 2026 B2B SaaS market selloff was caused by investors repricing software stocks around one belief: AI agents would shrink the human seats companies pay for. Software stocks lost over $1 trillion in six weeks after Anthropic’s Claude Cowork launch on January 30, 2026, with losses nearing $2 trillion by spring.
It didn’t build slowly. On February 3, 2026, Jeffrey Favuzza, an equity trader at Jefferies, coined the term that stuck for the rest of the year: “SaaSpocalypse.” He described the trading floor in three words, quoted directly via Bloomberg: “Trading is very much ‘get me out’ style selling.”
The trigger wasn’t an earnings miss or a rate hike. It was a product launch. Anthropic released Claude Cowork — a set of workplace automation tools — on January 30, 2026, and within days, institutional investors concluded that AI agents could already replace categories of work SaaS had been charging per seat, per month, to support.
The damage showed up immediately in the numbers:
- The iShares Expanded Tech-Software Sector ETF (IGV), the standard proxy for the SaaS sector, fell approximately 21% year-to-date by early February.
- Software stocks lost more than $1 trillion in combined market value in six weeks, according to AInvest data cited by Forbes.
- Salesforce fell roughly 26–30%, and other seat-billed categories — project management, CRM — took the sharpest hits, since task tracking and data entry are exactly what AI agents automate first.
- By spring 2026, cumulative software-sector losses approached $2 trillion, according to subsequent market coverage tracking the extended selloff.
This wasn’t a normal correction. It was a repricing of what “recurring revenue” even means once the thing generating that revenue — a human doing a task inside a seat — can be replaced by an agent doing the same task for a fraction of the cost.
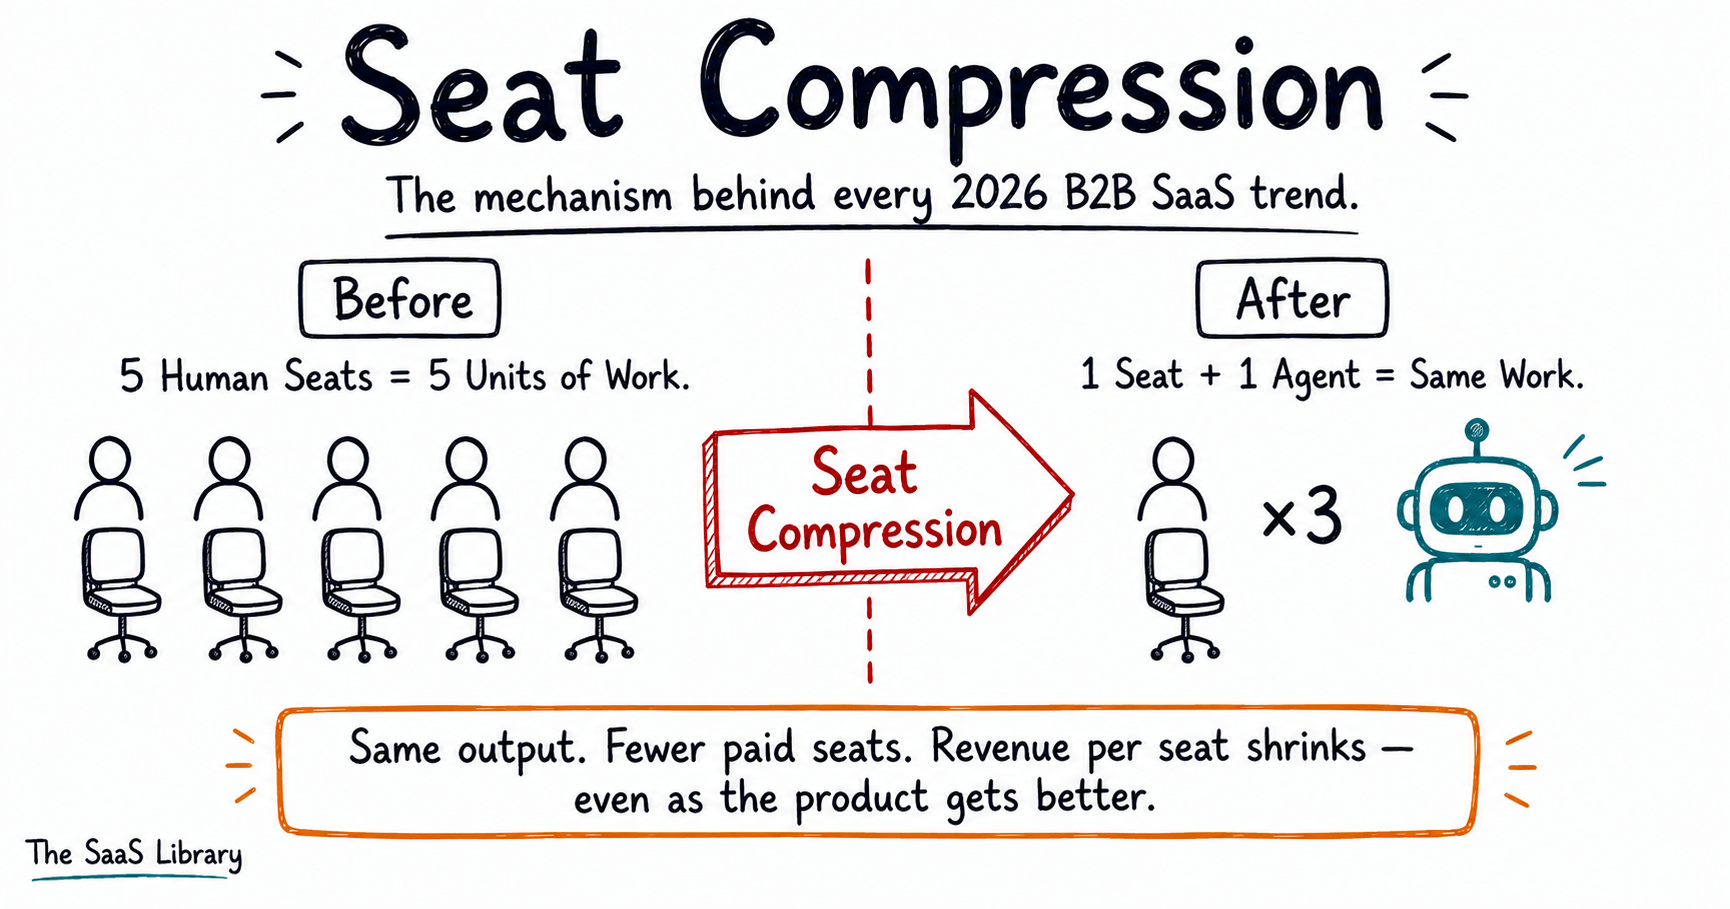
Seat Compression is what happens when an AI agent completes work that used to require a paid human seat, shrinking the number of seats a customer needs without shrinking the value that customer gets. It is the mechanism behind all five trends in this article: agents replace seats (Trend 1), pricing has to move off seats to survive (Trend 2), vertical and NRR-strong companies are the ones surviving compression (Trends 3–4), and enterprises are cutting the SaaS tools compression made redundant (Trend 5).
So what does this mean for the rest of B2B SaaS? Every trend covered in this article is a downstream reaction to Seat Compression — either a company adapting to it, profiting from it, or getting caught by it.
What Are the 5 B2B SaaS Trends in 2026?
- AI agents replacing features as the primary unit of software value.
- Per-seat pricing breaking down in favor of hybrid and usage-based models.
- Vertical SaaS outgrowing horizontal SaaS.
- Net revenue retention replacing ARR as the top valuation metric.
- Enterprises consolidating bloated SaaS portfolios.
All five are downstream effects of Seat Compression.
Here they are in order, each with the single stat that defines it.
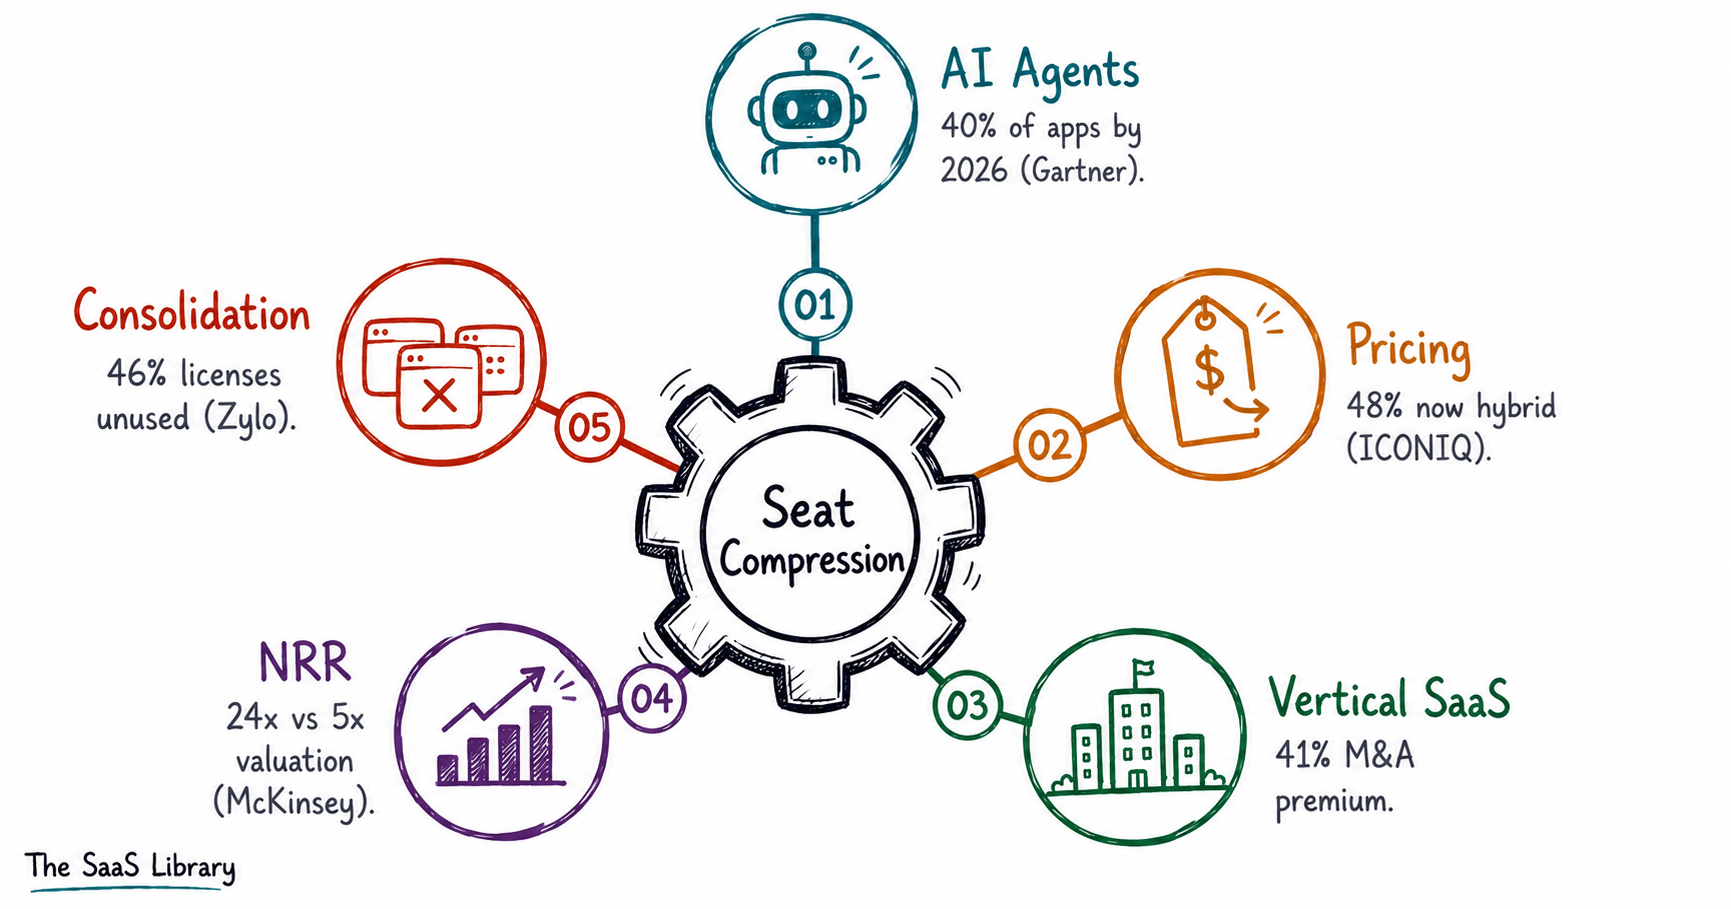
- AI agents are replacing features as the primary unit of SaaS value. Gartner forecasts that 40% of enterprise applications will embed task-specific AI agents by the end of 2026, up from less than 5% in 2025.
- Per-seat pricing is breaking down. 48% of B2B SaaS companies now run hybrid pricing as their primary model, according to ICONIQ Growth’s 2026 State of Go-to-Market report.
- Vertical SaaS is outgrowing horizontal SaaS. Vertical software companies grew at a median rate of roughly 31% in the past year, compared to about 28% for horizontal tools, and vertical SaaS sold at a 41% mergers-and-acquisitions (M&A) premium over horizontal SaaS in 2025 — the widest gap on record.
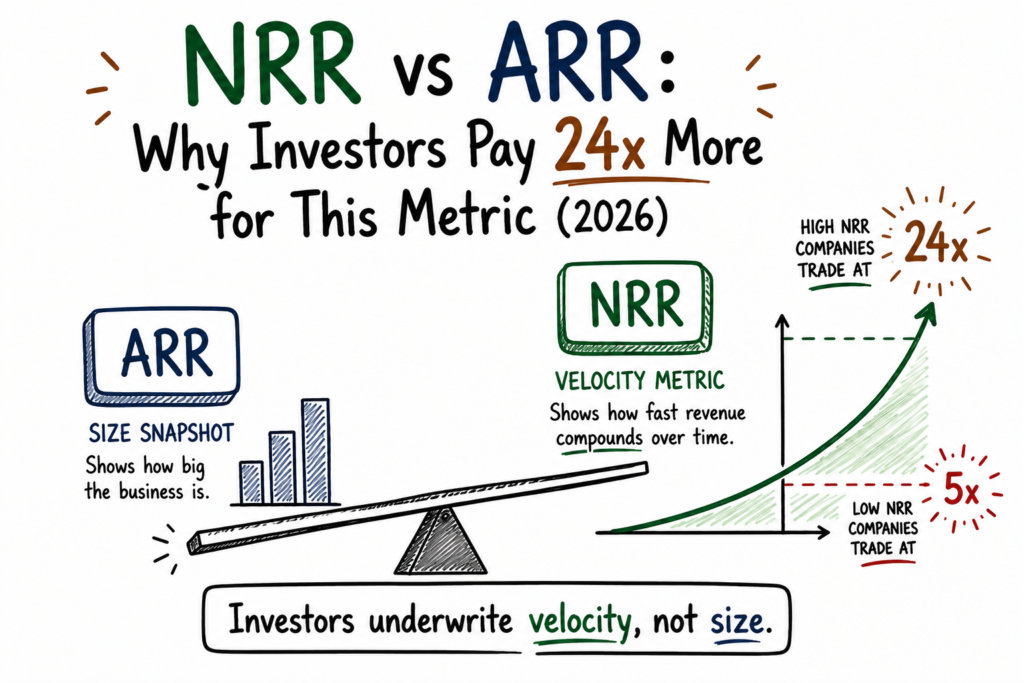
- Net revenue retention has replaced annual recurring revenue (ARR) as the metric investors actually price. McKinsey found that B2B SaaS companies in the top NRR quartile trade at a median 24x EV/Revenue, compared to just 5x for the bottom quartile.
- Enterprises are consolidating SaaS portfolios. The average enterprise now runs 305 SaaS applications and still leaves 46% of purchased licenses unused, per Zylo’s 2026 SaaS Management Index — pushing IT leaders to cut vendors rather than add them.
Want to see where AI agents are already working inside SaaS products today?
Read: AI Agents in SaaS: 8 Use Cases You Can Deploy Right Now →Each of these gets its own full breakdown next, starting with the trend causing all the others: AI agents.
How Are AI Agents Replacing Features as the Primary Unit of SaaS Value?
AI agents are replacing features as SaaS’s primary value unit by completing entire workflows autonomously instead of assisting a human through one. Gartner forecasts 40% of enterprise apps will embed task-specific agents by end of 2026, up from under 5% in 2025 — and Salesforce’s Agentforce already earns $800 million in annual recurring revenue.
A chatbot answers one question — the same distinction TSL breaks down in What Is the Difference Between an AI Agent and a Chatbot?. An agent perceives a situation, plans a response, acts on it, and checks the result — closer to a junior employee than a tool.
What Does the Adoption Data Actually Show?
The adoption data shows a market moving fast on paper and slowly in practice. Gartner projects an eightfold jump in enterprise agent embedding in a single year, but actual usage lags:
- 88% of organizations say they use AI regularly in at least one business function, up from 78% a year earlier, according to McKinsey’s November 2025 State of AI survey of 1,993 respondents across 105 countries.
- Only 23% report they are actively scaling an agentic AI system in any business function, while a further 39% are still experimenting.
- Gartner separately projects that over 40% of agentic AI projects will be cancelled by the end of 2027, citing escalating costs, unclear business value, and inadequate risk controls. That governance gap is stark on its own: 96% of companies are already running AI agents, and only 21% can actually control them.
Some of that hesitation comes from bad first experiences — buyers who tried an agent once and didn’t come back for a second attempt are a real, if under-discussed, part of the scaling gap.
Enterprise spending backs up the interest even where deployment lags. Companies spent $37 billion on generative AI in 2025, up from $11.5 billion in 2024 — a 3.2x jump, according to Menlo Ventures’ 2025 State of Generative AI in the Enterprise report. Anthropic’s share of enterprise LLM spend rose to 40% in that period, up from 24% the year before. That spending shift shows up directly in which models enterprises choose — a comparison The SaaS Library covers in detail.
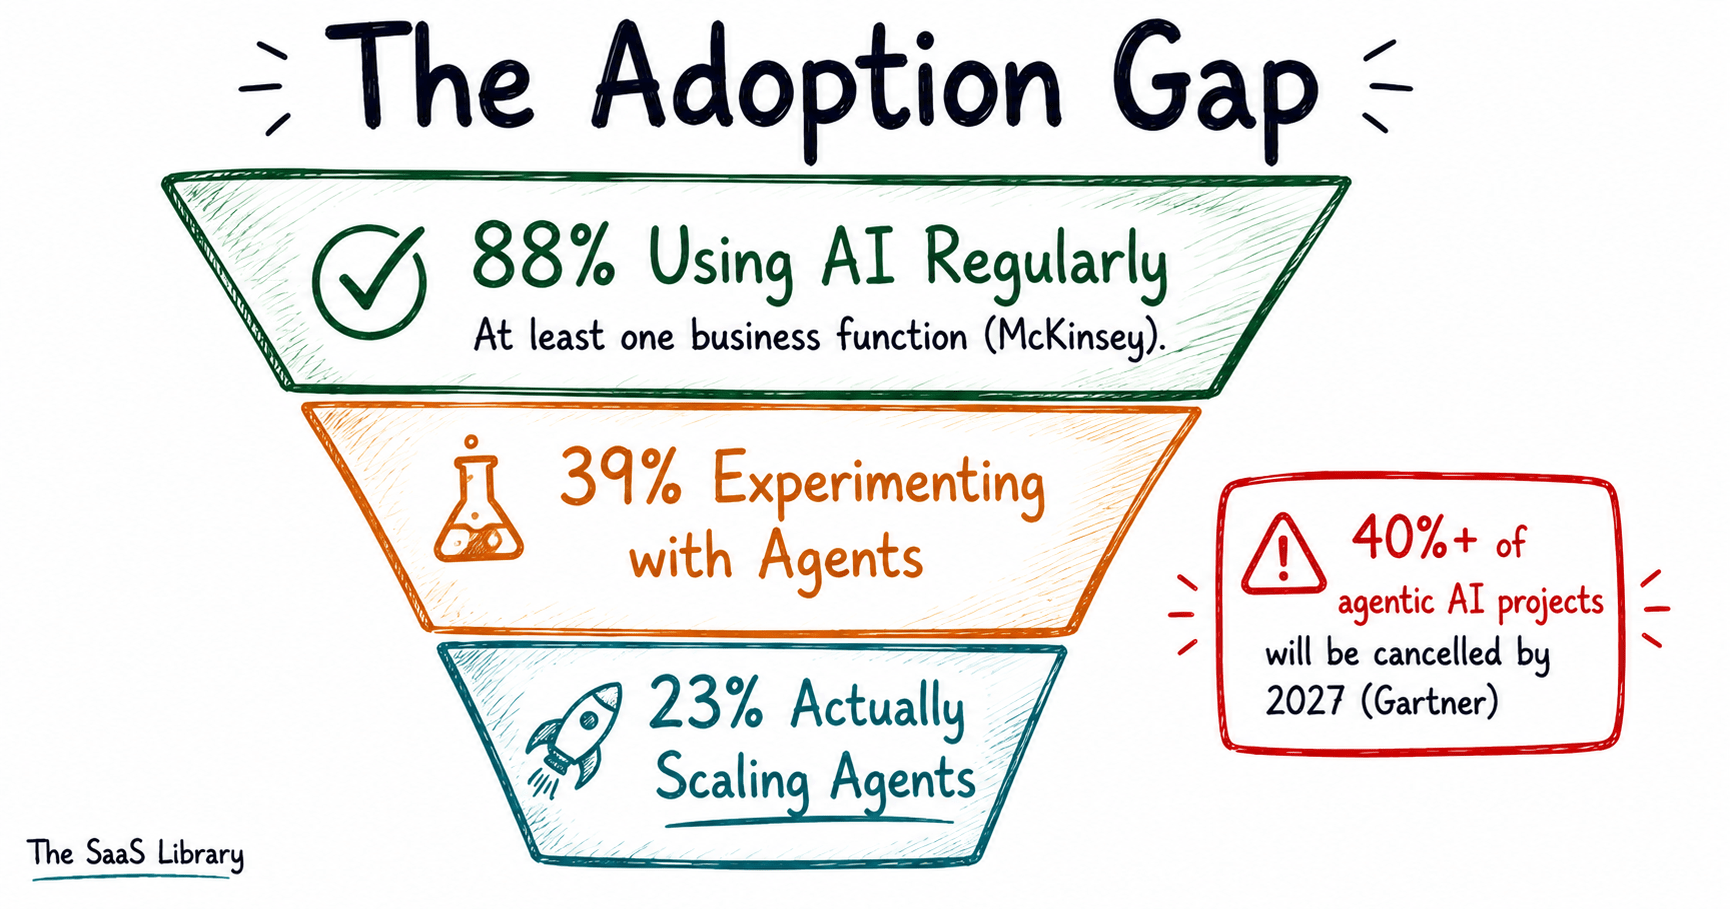
So the gap that matters isn’t whether companies are interested in agents. It’s the distance between “we’re experimenting” and “agents are running the operation” — and that distance is still wide for most enterprises.
Which Companies Are Already Proving the ROI?
The companies already proving the ROI are the ones embedding agents inside existing enterprise software rather than selling a separate agent product. Salesforce’s Agentforce platform reached $800 million in annual recurring revenue in Q4 fiscal 2026, up 169% year-over-year, closing 29,000 deals and processing 2.4 billion “agentic work units” to date.
One named customer result stands out. Wiley, the academic publisher, deployed Agentforce inside its Service Cloud support operation and reported a 213% return on investment, $230,000 in documented savings, 50% faster onboarding of seasonal support agents, and a 40% improvement in case resolution — all published directly by Salesforce as a customer case study.
The scale of the remaining opportunity is what makes this trend structural. Bain & Company estimates the US market for agentic coordination work at roughly $100 billion, of which only $4 to $6 billion is currently captured. Bain’s own framing, from its Technology Report 2025: “Disruption is mandatory. Obsolescence is optional.”
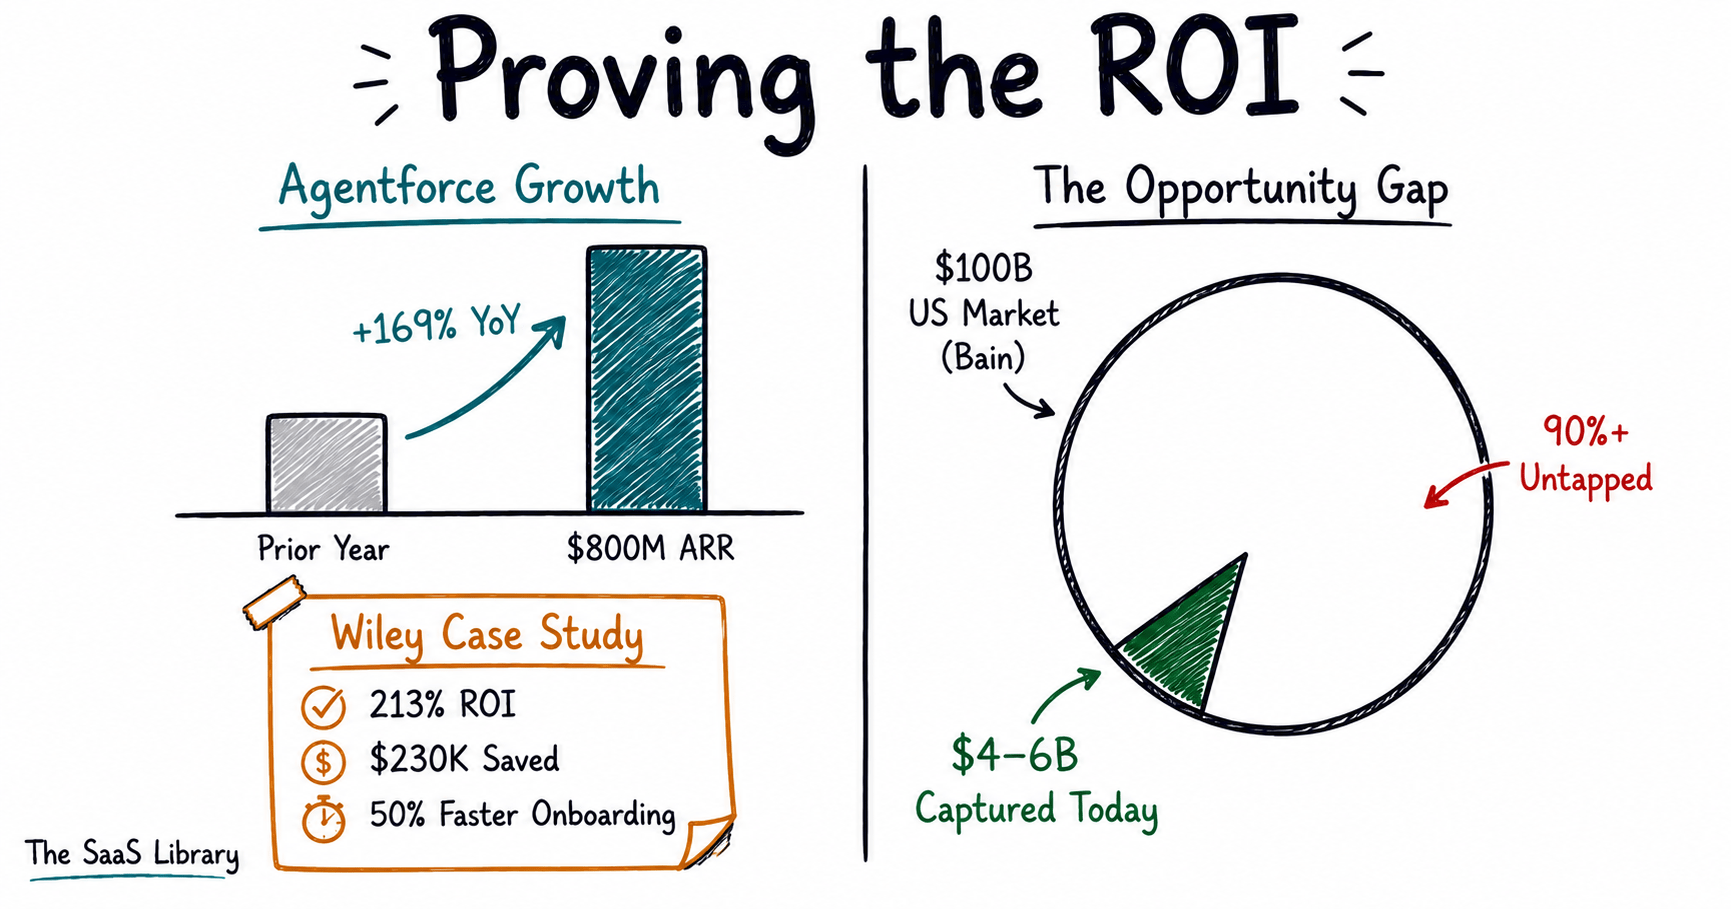
That’s a 90%-plus untapped opportunity sitting inside a single market. It’s also the reason legacy SaaS companies can’t just add a chatbot and call it done — the winners are the ones rebuilding the product around the agent, not bolting one on.
Why Is Per-Seat Pricing Breaking Down in B2B SaaS?
Per-seat pricing is breaking down in B2B SaaS because AI agents now complete work that used to require a paid human seat, so customers need fewer seats without needing less value. 48% of B2B SaaS companies run hybrid pricing as their primary model, per ICONIQ Growth’s 2026 State of Go-to-Market report.
It assumed one human, one seat, predictable consumption — the exact assumption The SaaS Library has already argued is dead. AI agents break that link — a single employee running three agents can generate the output of ten, and a vendor still billing per seat sees revenue shrink exactly when the product is working best.
What Pricing Models Are Replacing Per-Seat?
The pricing models replacing per-seat are hybrid and outcome-based structures that tie revenue to usage or results instead of headcount. Compensation is following the same shift — ICONIQ’s report states directly: “As pricing shifts toward hybrid and consumption/usage models, Account Executives are increasingly being tied to Net New Recurring Revenue and Net Dollar Retention to help reinforce sustainable revenue expansion over time.”
Intercom’s Fin is the clearest live example of pure outcome-based pricing in mainstream B2B SaaS:
- $0.99 per resolution — a conversation the AI agent closes without a human stepping in.
- $0.99 per procedure handoff and $0.99 per disqualification.
- $9.99 per lead qualification.
- A minimum of 50 billable outcomes per month, putting the pricing floor around $49.50.
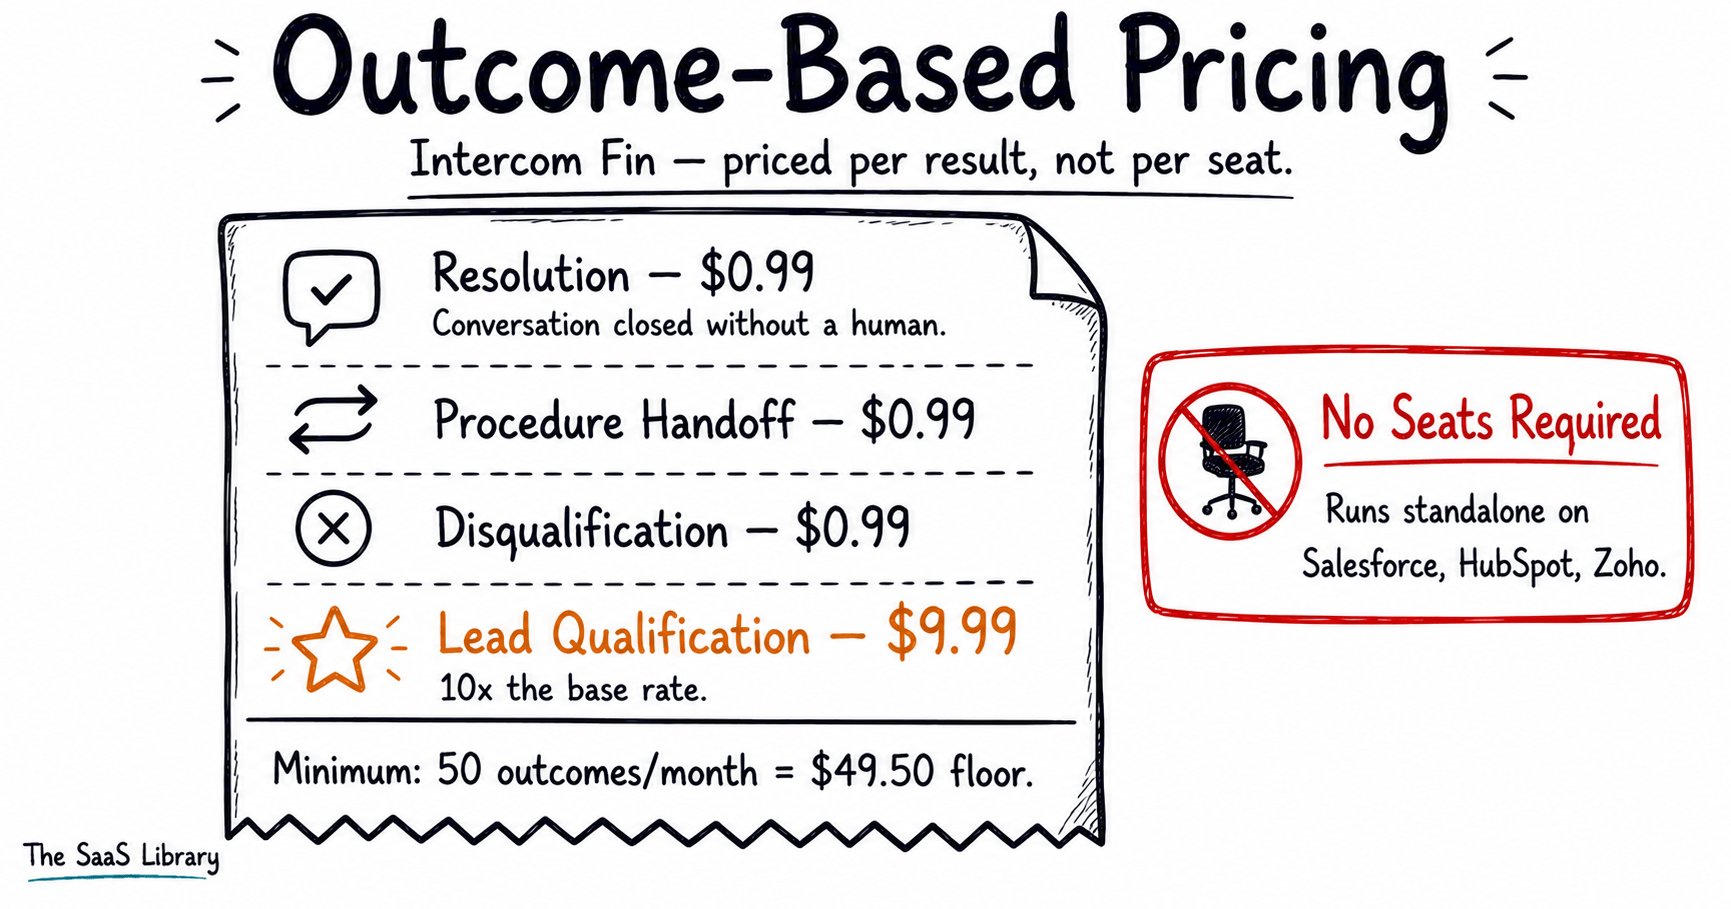
Fin can also run standalone on top of an existing helpdesk — including Salesforce, HubSpot, and Zoho — with no seats required at all, according to Intercom’s own pricing page.
The clearest proof this model is going mainstream came on June 15, 2026: Salesforce signed a definitive agreement to acquire Fin, formerly Intercom, for approximately $3.6 billion, folding its outcome-priced AI agent directly into Agentforce. CEO Marc Benioff said the deal would help companies “accelerate time to value with trusted agents that deliver measurable outcomes at scale.”
How Does Pricing Model Choice Affect Net Revenue Retention?
Pricing model choice affects net revenue retention because consumption pricing scales revenue automatically as customer usage grows, while flat subscription fees require a separate upsell motion to do the same thing. Snowflake reported 125% net revenue retention in Q4 of its fiscal 2026 on annual revenue of $4.68 billion, and Datadog posted approximately 120% NRR on $3.43 billion in 2025 revenue — both companies price on consumption, not seats.
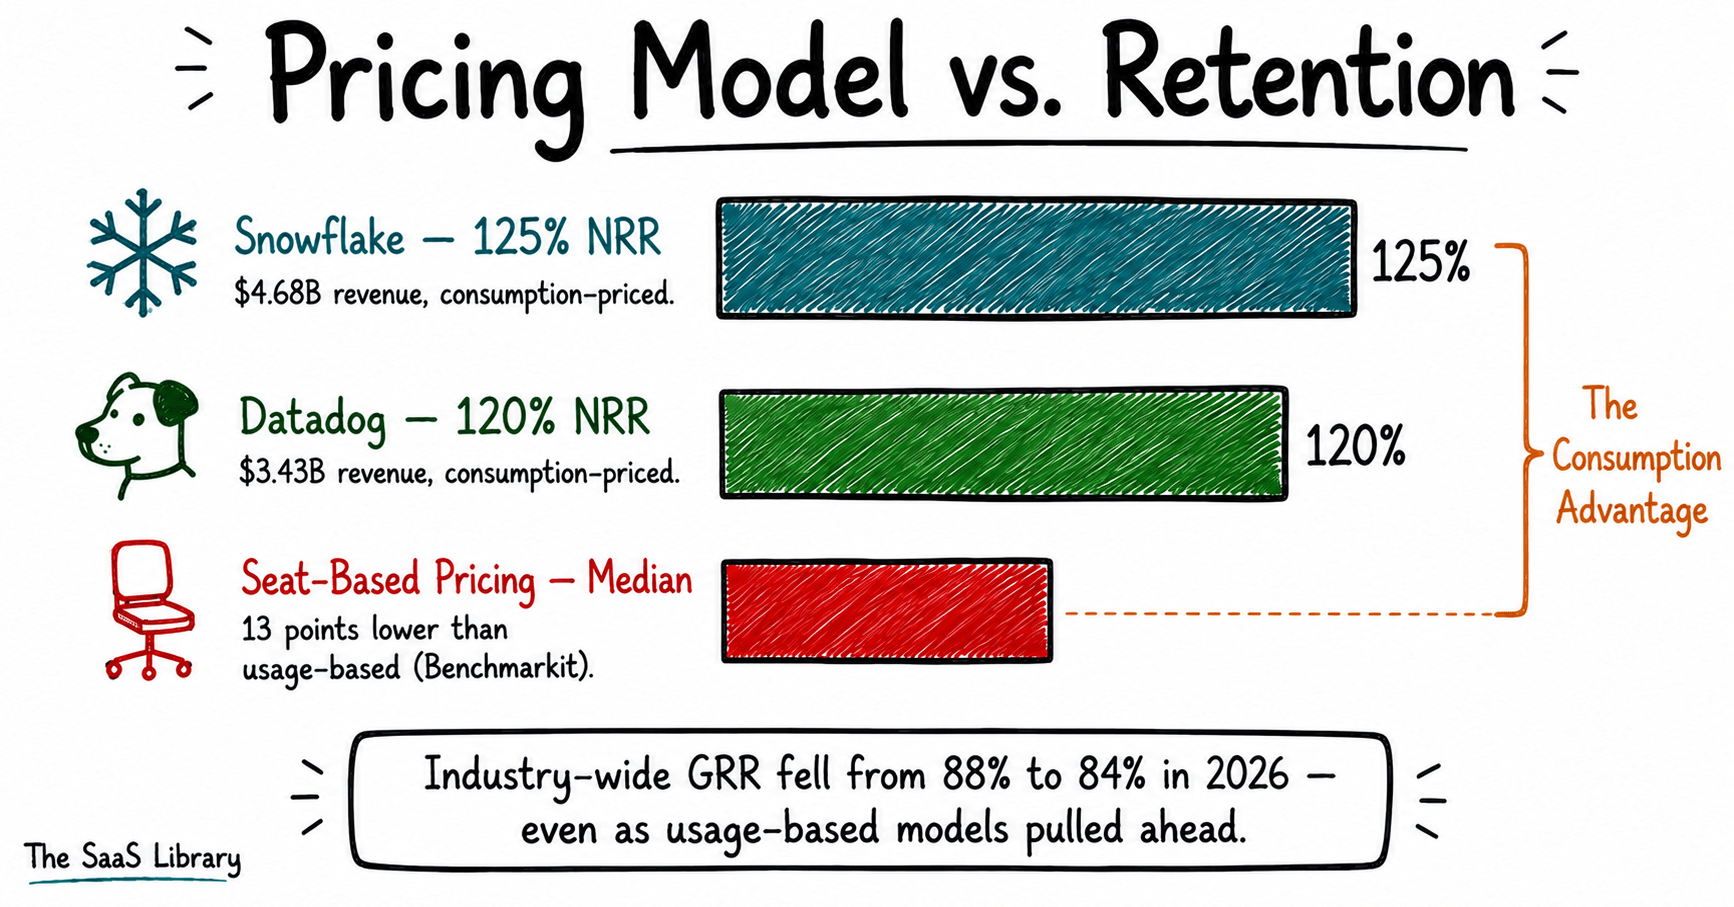
The gap shows up broadly, not just at the top two names. Benchmarkit’s 2026 B2B SaaS & AI-Native Metrics report found usage-based and hybrid pricing models carry roughly a 13-point NRR advantage over seat-based pricing, even as the median gross revenue retention across B2B SaaS fell from 88% to 84% industry-wide.
So the pricing shift isn’t cosmetic. Companies that move revenue off seats and onto usage are the ones showing up with retention numbers strong enough to justify the valuation premiums covered in the next section.
Why Is Vertical SaaS Outgrowing Horizontal SaaS in 2026?
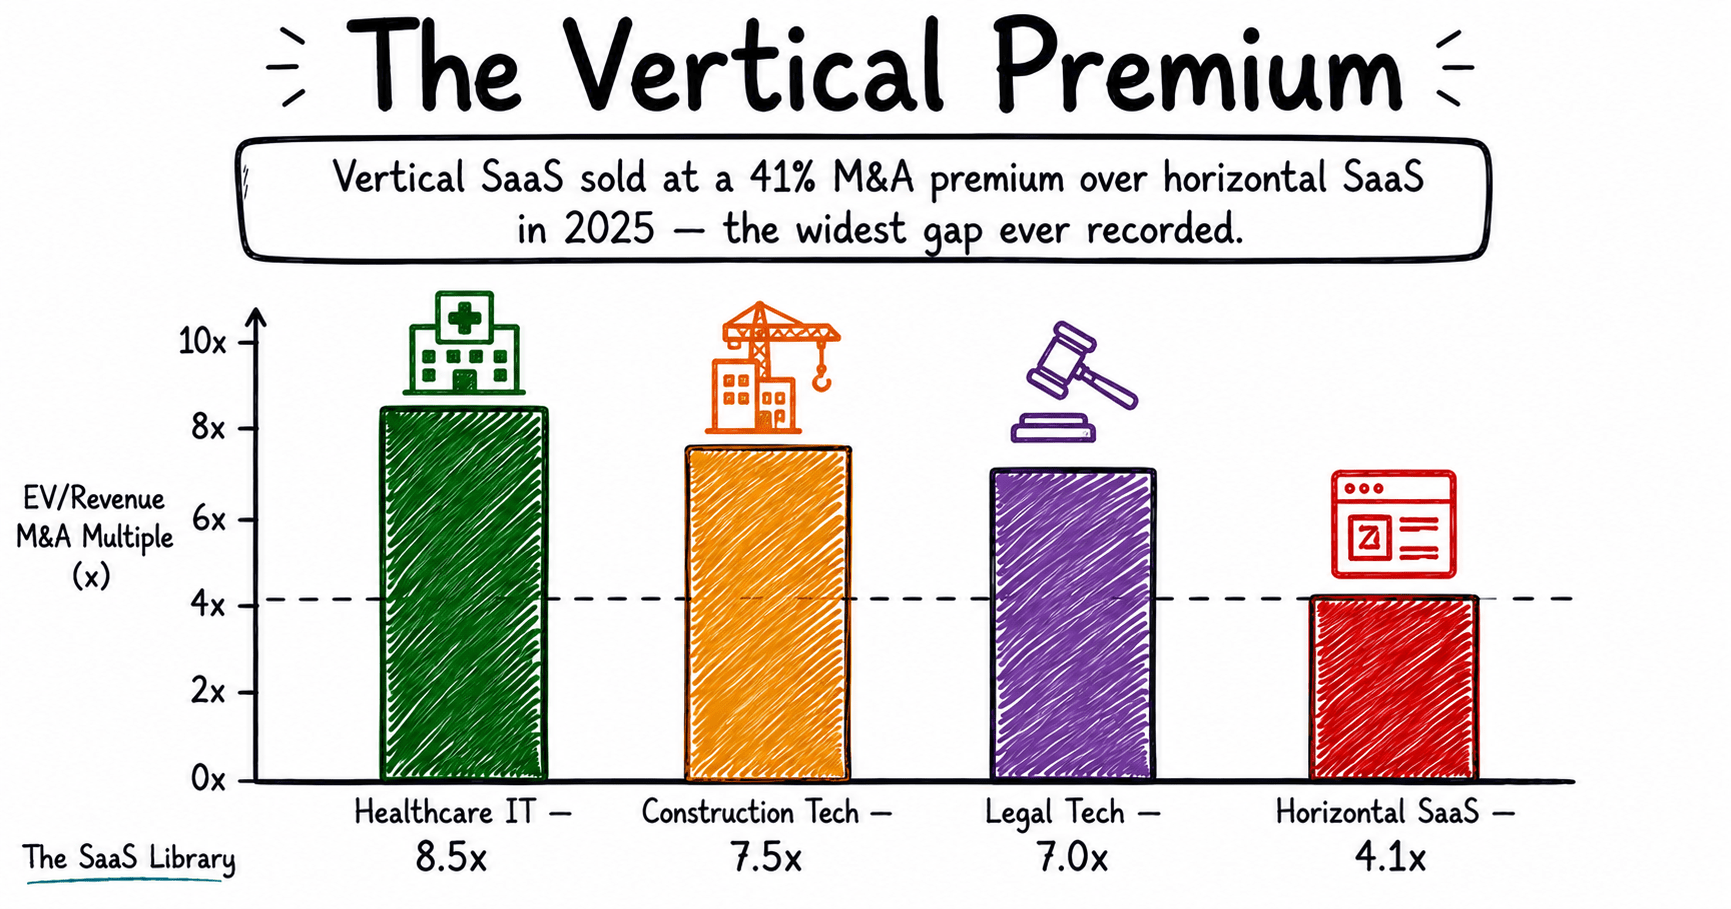
Vertical SaaS is outgrowing horizontal SaaS in 2026 because industry-specific software builds deeper data moats and higher switching costs. Vertical companies grew at a median 31% in the past year versus 28% for horizontal tools, and sold at a 41% M&A premium over horizontal SaaS in 2025 — the widest gap ever recorded.
Buyers pay more for vertical software because it’s harder to rip out. A hospital’s billing platform, a construction firm’s project-cost system, or a law firm’s matter-management tool is wired into regulatory compliance and daily workflow in a way a generic CRM never is.
What Is Creating the Vertical SaaS Moat?
The vertical SaaS moat is created by three things compounding together: proprietary industry data, regulatory compliance built in from day one, and workflow integration deep enough that switching means re-training an entire team. An analysis of more than 1,275 M&A transactions and 2,300+ VC rounds found vertical SaaS companies traded at a median 5.8x EV/Revenue in M&A deals in 2025, versus 4.1x for horizontal SaaS — a 41% premium, the widest gap on record.
The premium widens further inside the highest-compliance verticals:
- Healthcare IT commanded 8.5x revenue in M&A transactions.
- Construction tech commanded 7.5x.
- Legal tech commanded 7.0x.
- Generic horizontal SaaS, increasingly commoditized by AI, sat at 4.1x.
Private equity has noticed. PE buyers were involved in roughly 57–58% of all SaaS transactions in 2025, actively building vertical platforms through acquisitions in exactly these categories.
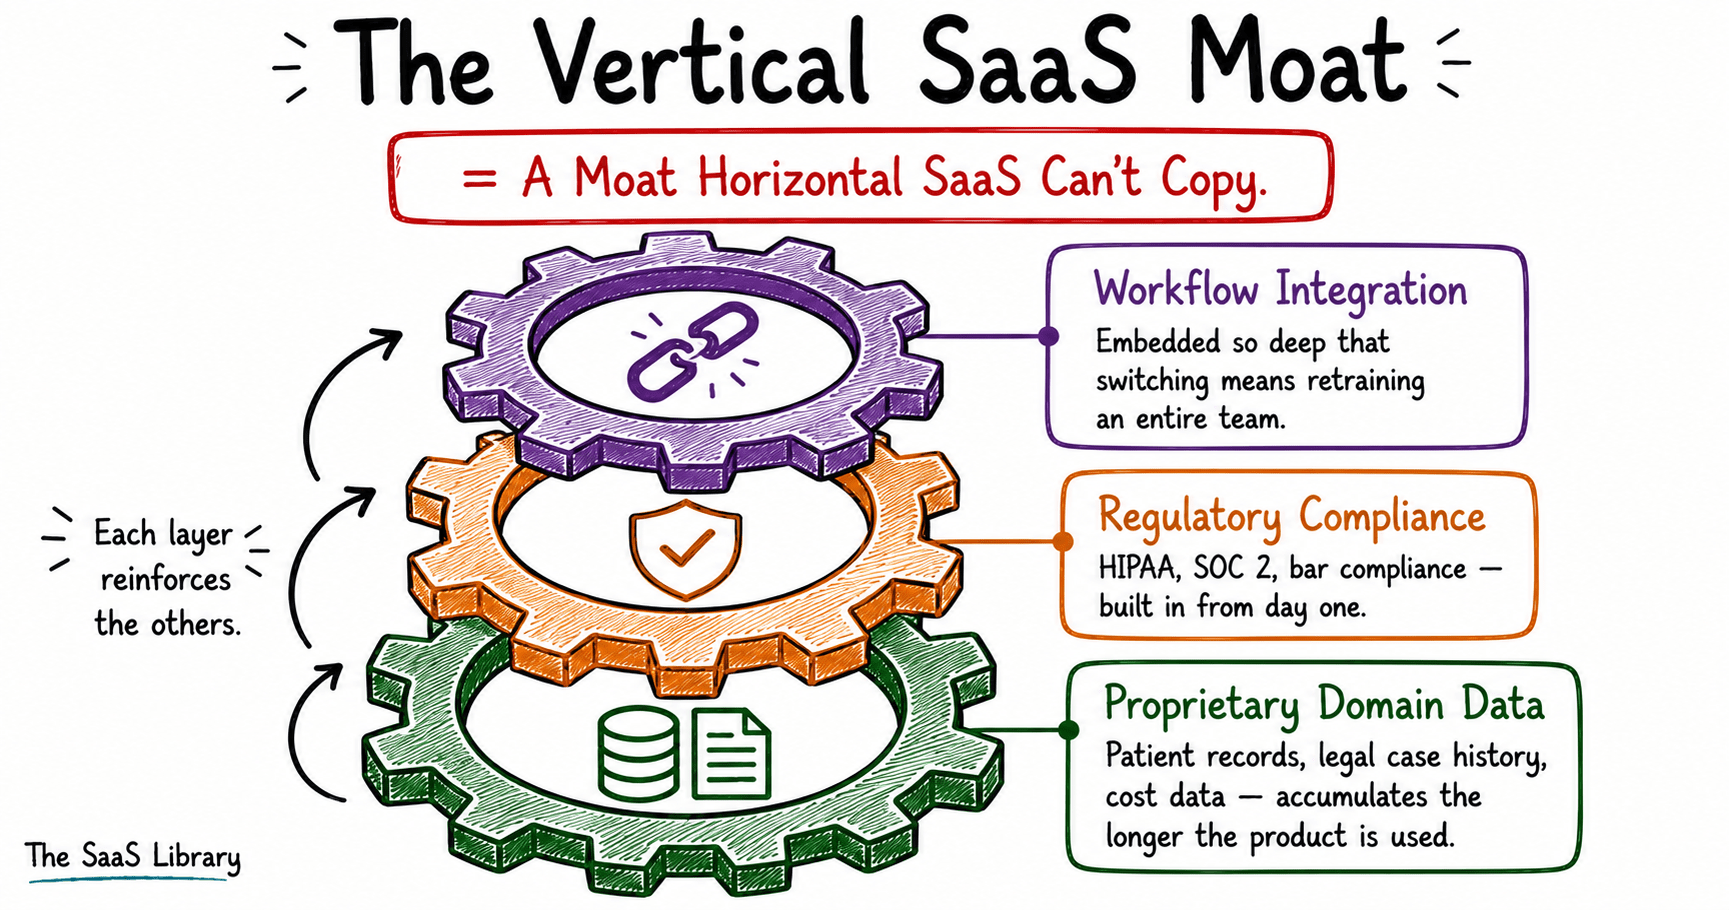
The mechanism explains why: domain-specific AI trained on an industry’s own data — patient records, legal case history, construction cost data — outperforms a general-purpose model applied to the same task, and that performance gap is a moat a horizontal competitor can’t copy by adding a chatbot. The global vertical software market was valued at $164.06 billion in 2026, on track for $282.98 billion by 2031, according to Mordor Intelligence — and healthcare, insurance, and construction remain among its largest and fastest-growing categories.
That’s the strategic split worth remembering: horizontal SaaS competes on breadth, but vertical SaaS competes on depth — and depth is what AI is currently rewarding.
Why Has NRR Replaced ARR as B2B SaaS’s Primary Health Metric?
NRR has replaced ARR as B2B SaaS’s primary health metric because investors now price retention quality above growth rate. McKinsey found top-NRR-quartile companies trade at a median 24x EV/Revenue versus 5x for the bottom quartile — a gap ARR growth alone doesn’t explain.
ARR answers “how much revenue came in.” NRR answers “did the customers I already have get more or less valuable this year” — the full case for why investors pay up to 24x more for this one metric is worth reading in full.
What Do Current NRR Benchmarks Look Like by Company Size?
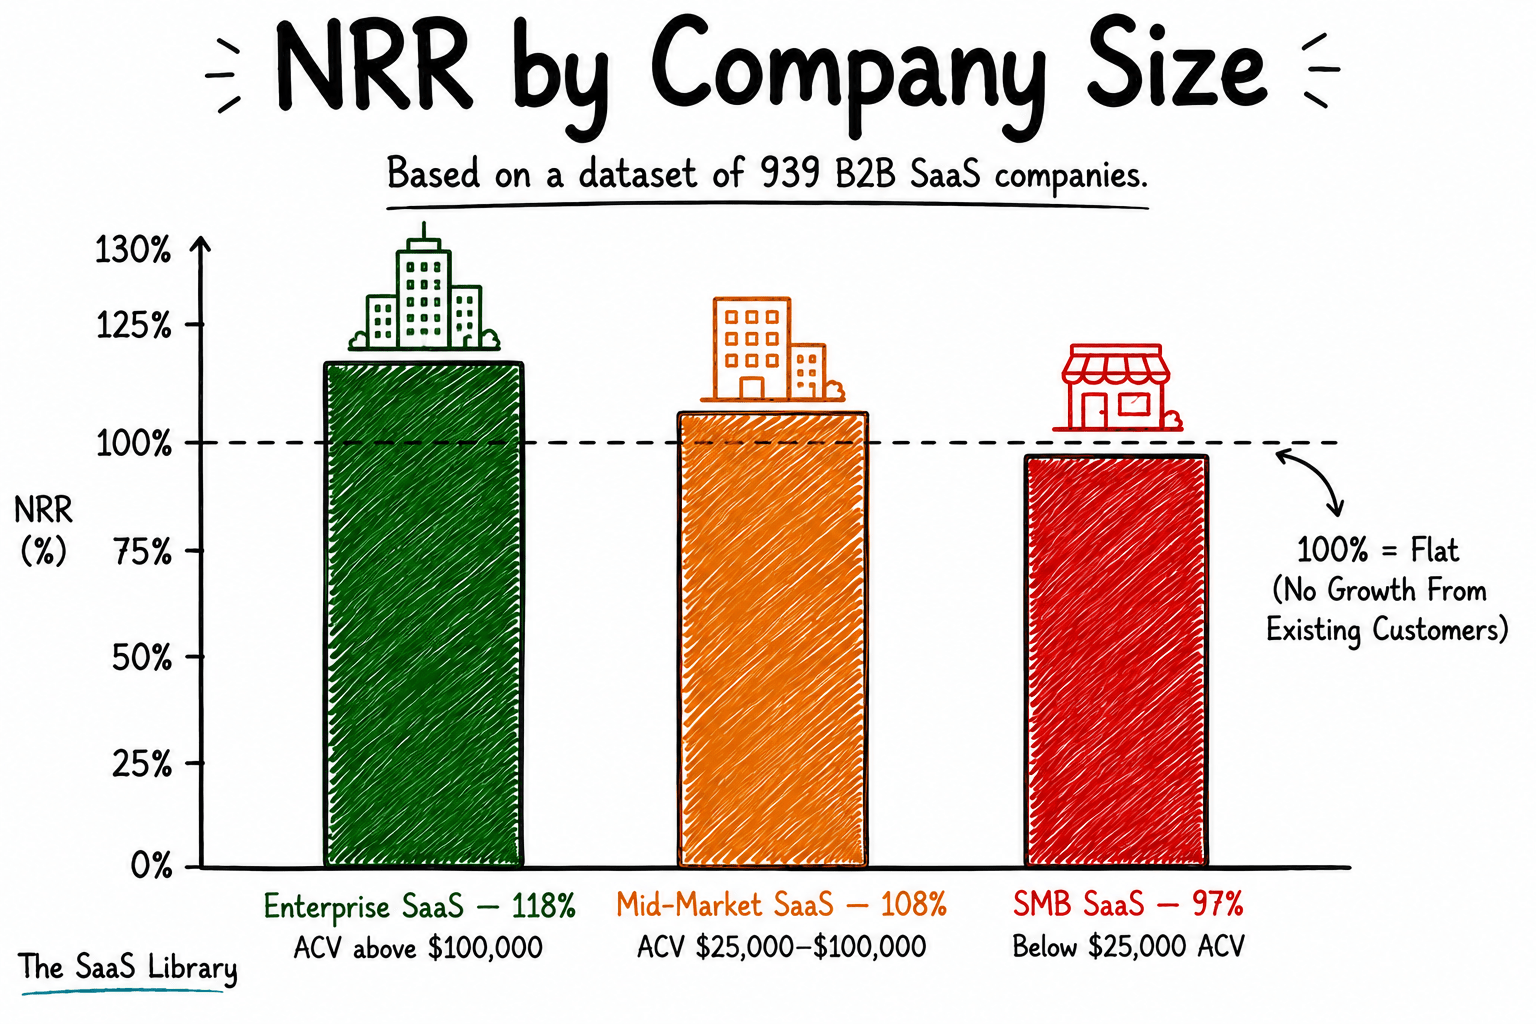
Current NRR benchmarks vary sharply by company size, and the gap is wide enough that comparing a small company to an enterprise one on the same NRR number is misleading. Across a dataset of 939 B2B SaaS companies:
- Enterprise SaaS (average contract value, or ACV, above $100,000) posts a median NRR of 118%.
- Mid-market SaaS ($25,000–$100,000 ACV) comes in at 108%.
- SMB-focused SaaS sits at 97% — meaning the median SMB SaaS company is actually shrinking within its existing customer base before counting any new sales.
Private, bootstrapped companies tell a similar story at a slightly lower baseline. SaaS Capital’s 2026 survey of more than 1,000 private B2B SaaS companies found a median NRR of 103%, with the 90th percentile reaching 117.9% and median gross revenue retention at 91%.
The takeaway is segment-specific, not universal: a 105% NRR at an enterprise company signals underperformance, while the same number at an SMB-focused product is roughly the market median.
Why Are AI-Native Companies Showing Weaker NRR?
AI-native companies are showing weaker NRR because a large share of their early customer base signed up out of curiosity, not committed workflow need. ChartMogul’s analysis of 3,500 software businesses found AI-native companies posting a median NRR of just 48% and gross revenue retention of 40%, compared to a median NRR of 82% for conventional B2B SaaS in the same dataset.
Kyle Poyar, Analyst-in-Residence at ChartMogul, calls this the “AI tourist effect” — users who “sign up out of curiosity and, like tourists, leave before activating because there is no recurring use case.”
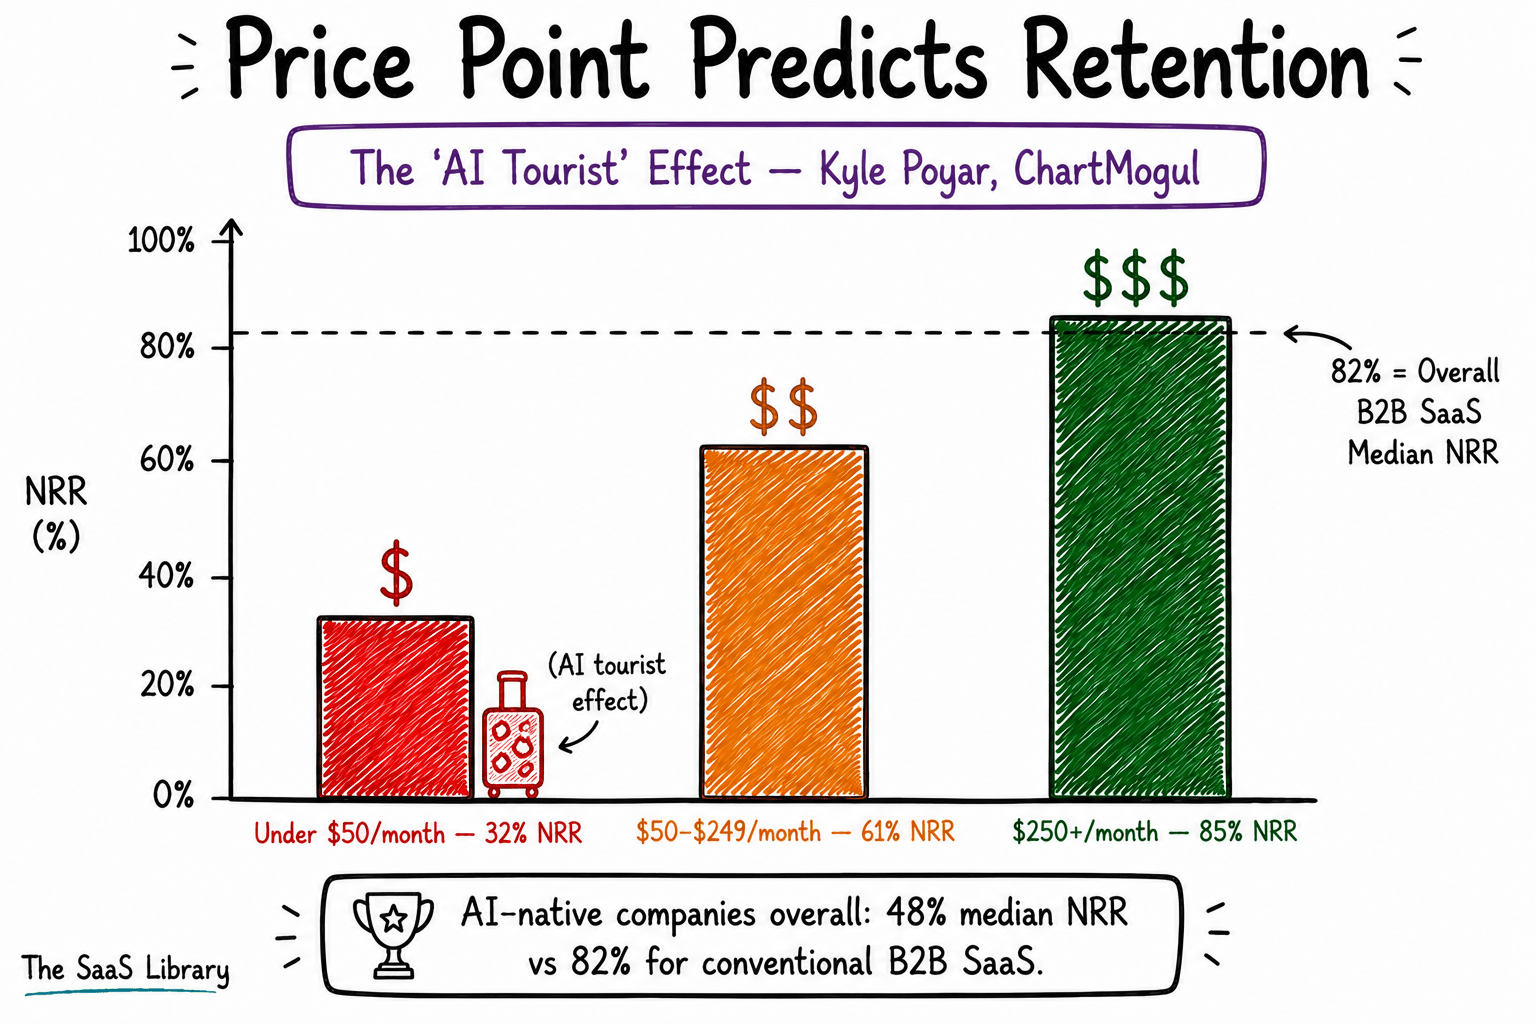
Price point turns out to be the strongest predictor of which AI products keep customers and which don’t:
- AI products priced above $250 per month retain at roughly 85% NRR and 70% GRR — in line with traditional B2B SaaS.
- Products priced $50–$249 per month retain at roughly 61% NRR.
- Products priced under $50 per month retain at just 32% NRR, with GRR as low as 23%.
There is a recovery trend worth noting: AI-native median GRR climbed from 27% in January 2025 to 40% by September 2025, as the earliest wave of curious “tourists” churned out and left a smaller, more committed customer base behind. But even that improved number still sits well below the B2B SaaS median — a reminder that “AI-native” alone isn’t a retention strategy, and cheap, low-commitment AI tools remain highly disposable.
That gap is exactly why NRR, not user growth or ARR, is the number worth watching before betting on any AI-native SaaS company’s staying power.
Why Is SaaS Portfolio Consolidation Accelerating?
SaaS portfolio consolidation is accelerating because enterprises pay for far more software than they use, and unpredictable AI-driven pricing is forcing budget owners to cut vendors rather than add them. The average organization runs 305 SaaS applications and leaves 46% of licenses unused, per Zylo’s 2026 SaaS Management Index.
That waste isn’t new. What’s new is that budget owners finally have the pricing pressure to act on it, since AI-driven consumption billing is making SaaS bills unpredictable at the exact moment finance teams are looking to cut.
What Do the Latest Enterprise Numbers Show?
The latest enterprise numbers show a portfolio that has stopped growing in size but keeps growing in cost. Zylo’s 2026 SaaS Management Index — built on more than 40 million licenses and $75 billion in spend under management — found:
- The average organization now spends $55.7 million annually on SaaS, up 8% year-over-year, even as the average portfolio holds flat at 305 applications.
- 46% of licenses go unused in a given month (utilization improved from 47% to 54% year-over-year), representing $19.8 million in annual waste.
- 78% of IT leaders reported unexpected charges tied to consumption-based or AI pricing models in the past 12 months, and 61% were forced to cut projects because of unplanned SaaS cost increases.
- Business units now control 81% of SaaS spend, while IT directly manages just 15% — visibility is declining exactly as pricing gets more volatile.
- AI-native application spend grew 393% year-over-year at large enterprises, and ChatGPT is now the single most-expensed application inside the average organization.
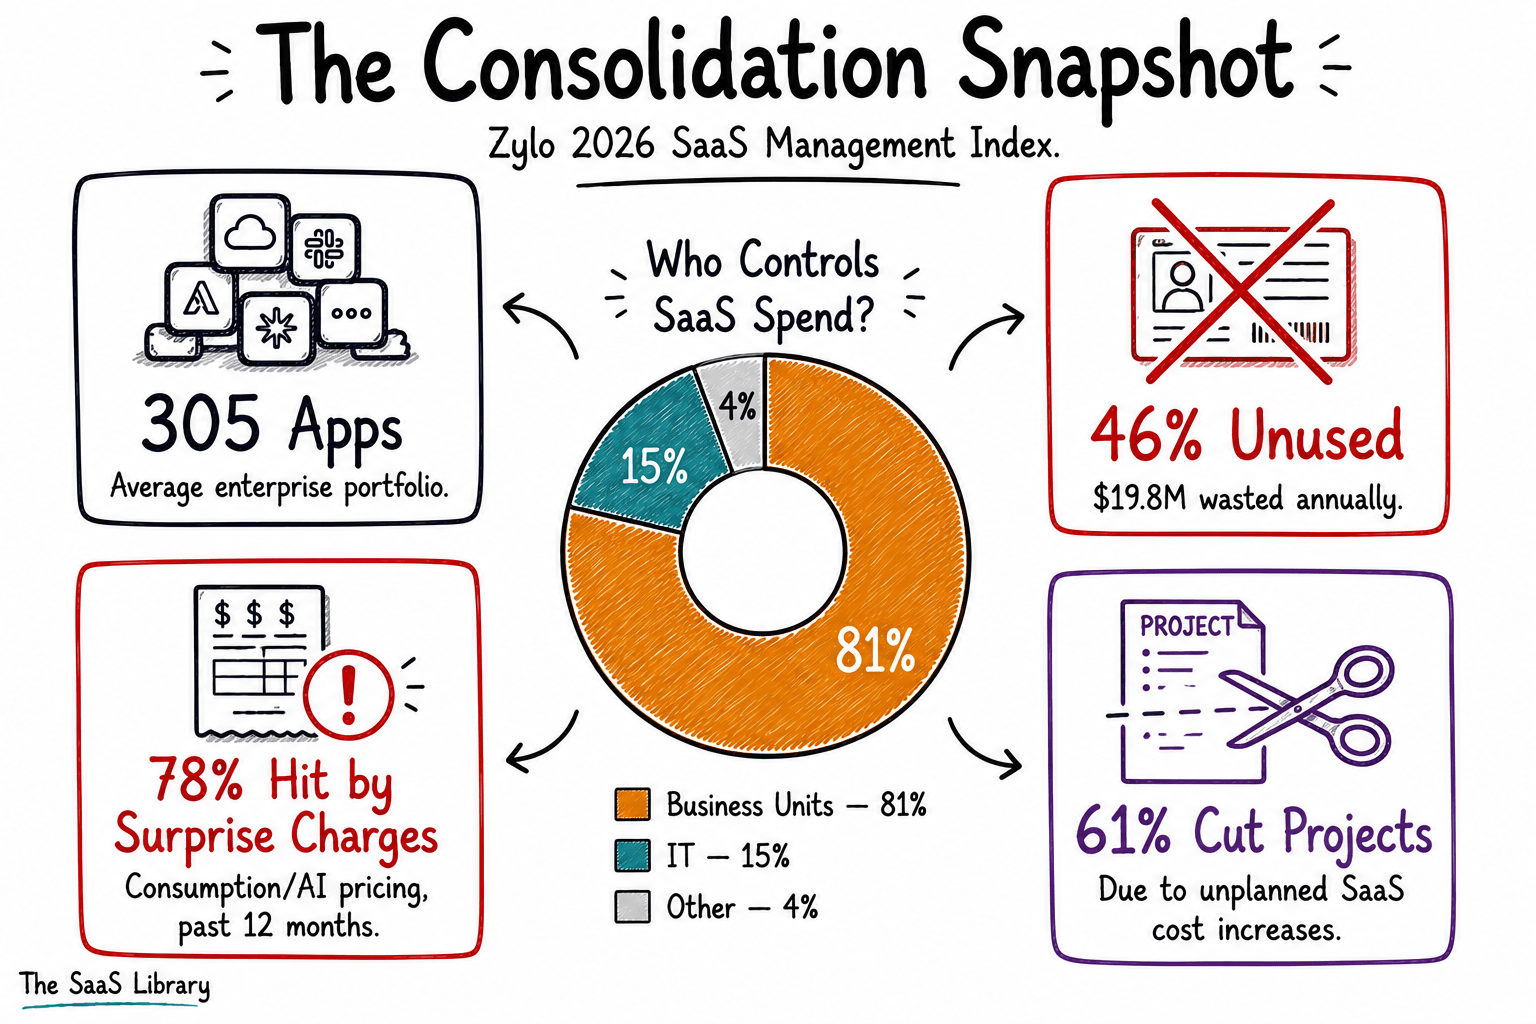
Gartner reinforces the same pattern from the buying side: by 2027, 70% of organizations will consolidate their cloud-native application vendors down to a maximum of three strategic providers, and organizations without centralized SaaS visibility will overspend by at least 25% through 2028.
The pattern across every number here points the same direction: the sprawl problem stopped being about how many tools a company owns and became about which tools survive the next renewal cycle — and this trend, unlike the other four, is the one where the customer, not the vendor, decides who wins.
How Has B2B SaaS Changed Before and After 2026?
B2B SaaS changed before and after 2026 by moving from feature-based AI, per-seat pricing, growth-at-all-costs, and unchecked tool sprawl toward agent-native products, usage-based pricing, retention-led valuation, and deliberate portfolio consolidation — all triggered by the Seat Compression repricing covered at the start of this article.
Laid side by side across six dimensions, the shift isn’t subtle.
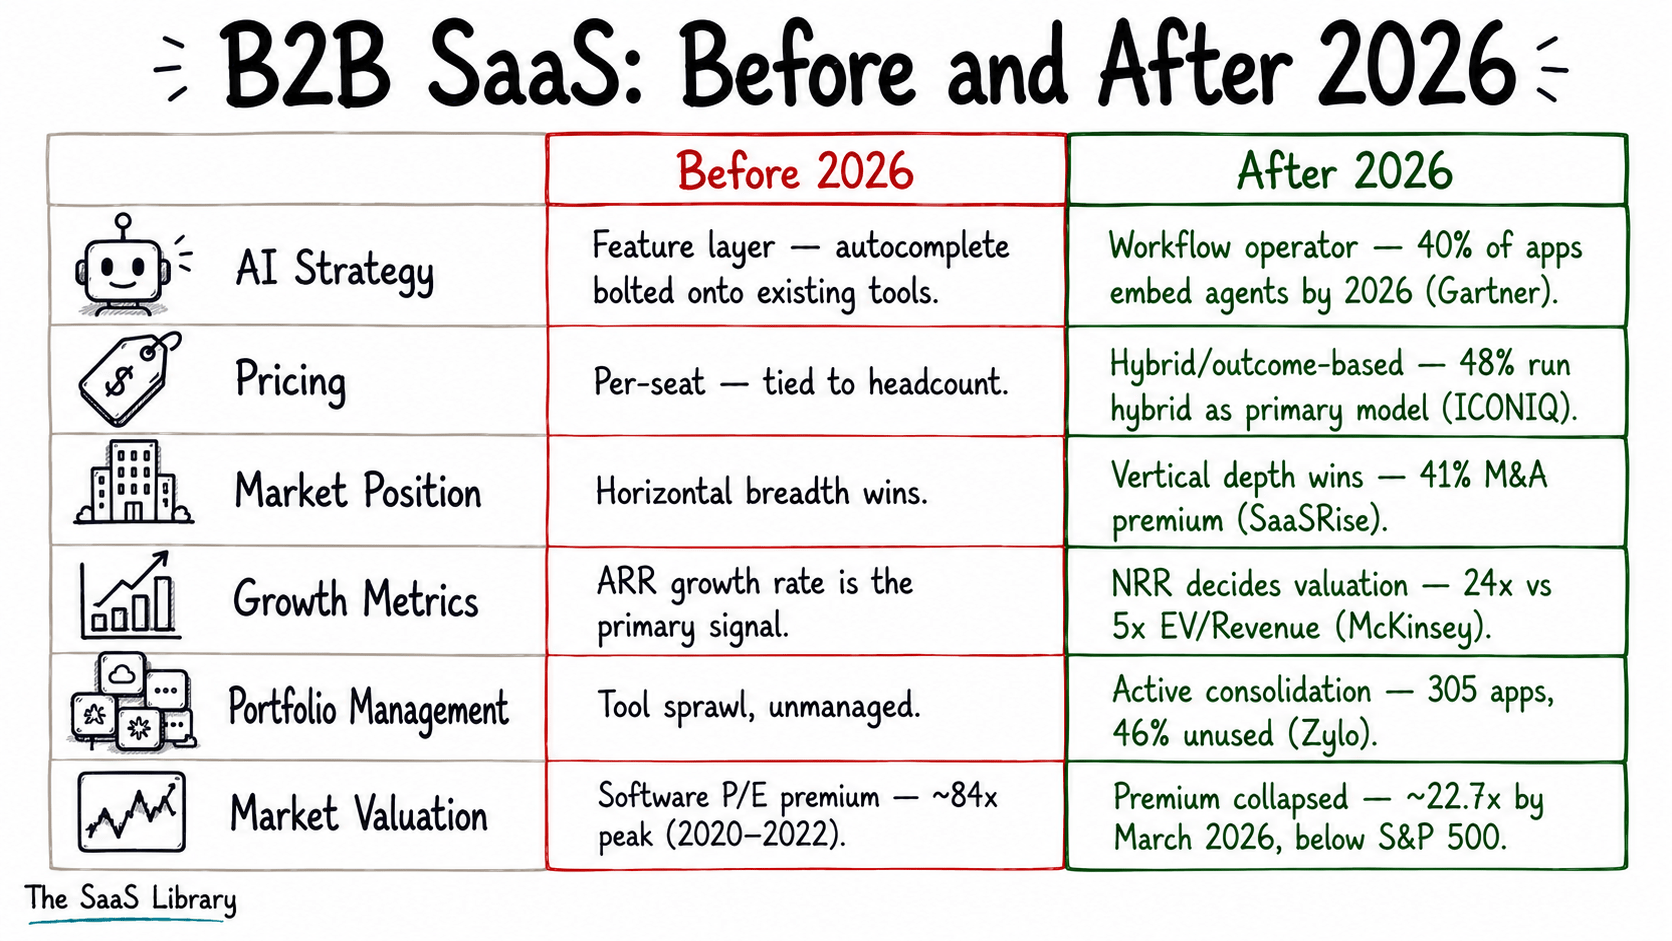
| Dimension | Before 2026 | After 2026 |
|---|---|---|
| AI Strategy | Feature layer — autocomplete bolted onto existing tools. | Workflow operator — 40% of apps embed agents by 2026 (Gartner). |
| Pricing | Per-seat — tied to headcount. | Hybrid/outcome-based — 48% run hybrid as primary model (ICONIQ). |
| Market Position | Horizontal breadth wins. | Vertical depth wins — 41% M&A premium (SaaSRise). |
| Growth Metrics | ARR growth rate is the primary signal. | NRR decides valuation — 24x vs 5x EV/Revenue (McKinsey). |
| Portfolio Management | Tool sprawl, unmanaged. | Active consolidation — 305 apps, 46% unused (Zylo). |
| Market Valuation | Software P/E premium — ~84x peak (2020–2022). | Premium collapsed — ~22.7x by March 2026, below S&P 500. |
Read across all six rows, and the pattern is the same one this article opened with — every dimension of B2B SaaS that used to reward scale and seat count now rewards:
- Depth.
- Retention.
- Agent-native product design.
Which B2B SaaS Strategy Fits Your Stage?
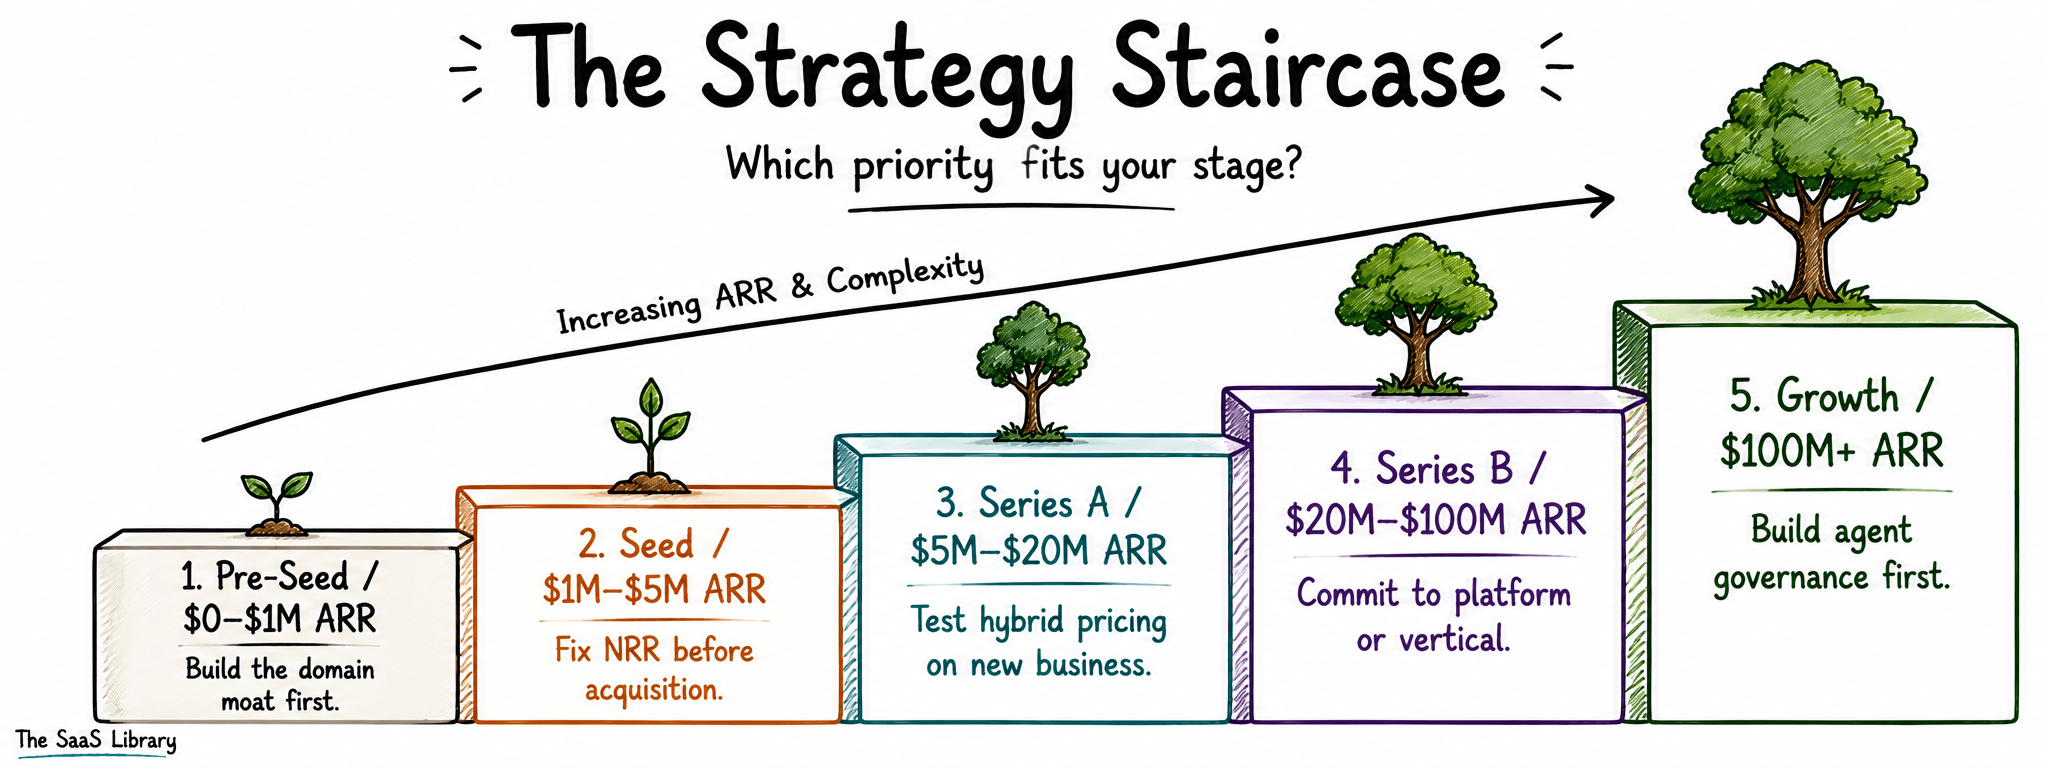
The right B2B SaaS strategy depends on ARR stage: pre-seed companies build a domain moat first, seed-stage companies fix NRR before spending on acquisition, Series A tests hybrid pricing on new business, Series B commits to platform or vertical depth, and growth-stage companies treat agent governance as table stakes.
Seat Compression doesn’t hit every company the same way. The right response depends entirely on how much revenue, and how much time, a company has to adapt.
What Should You Actually Do About These Trends?
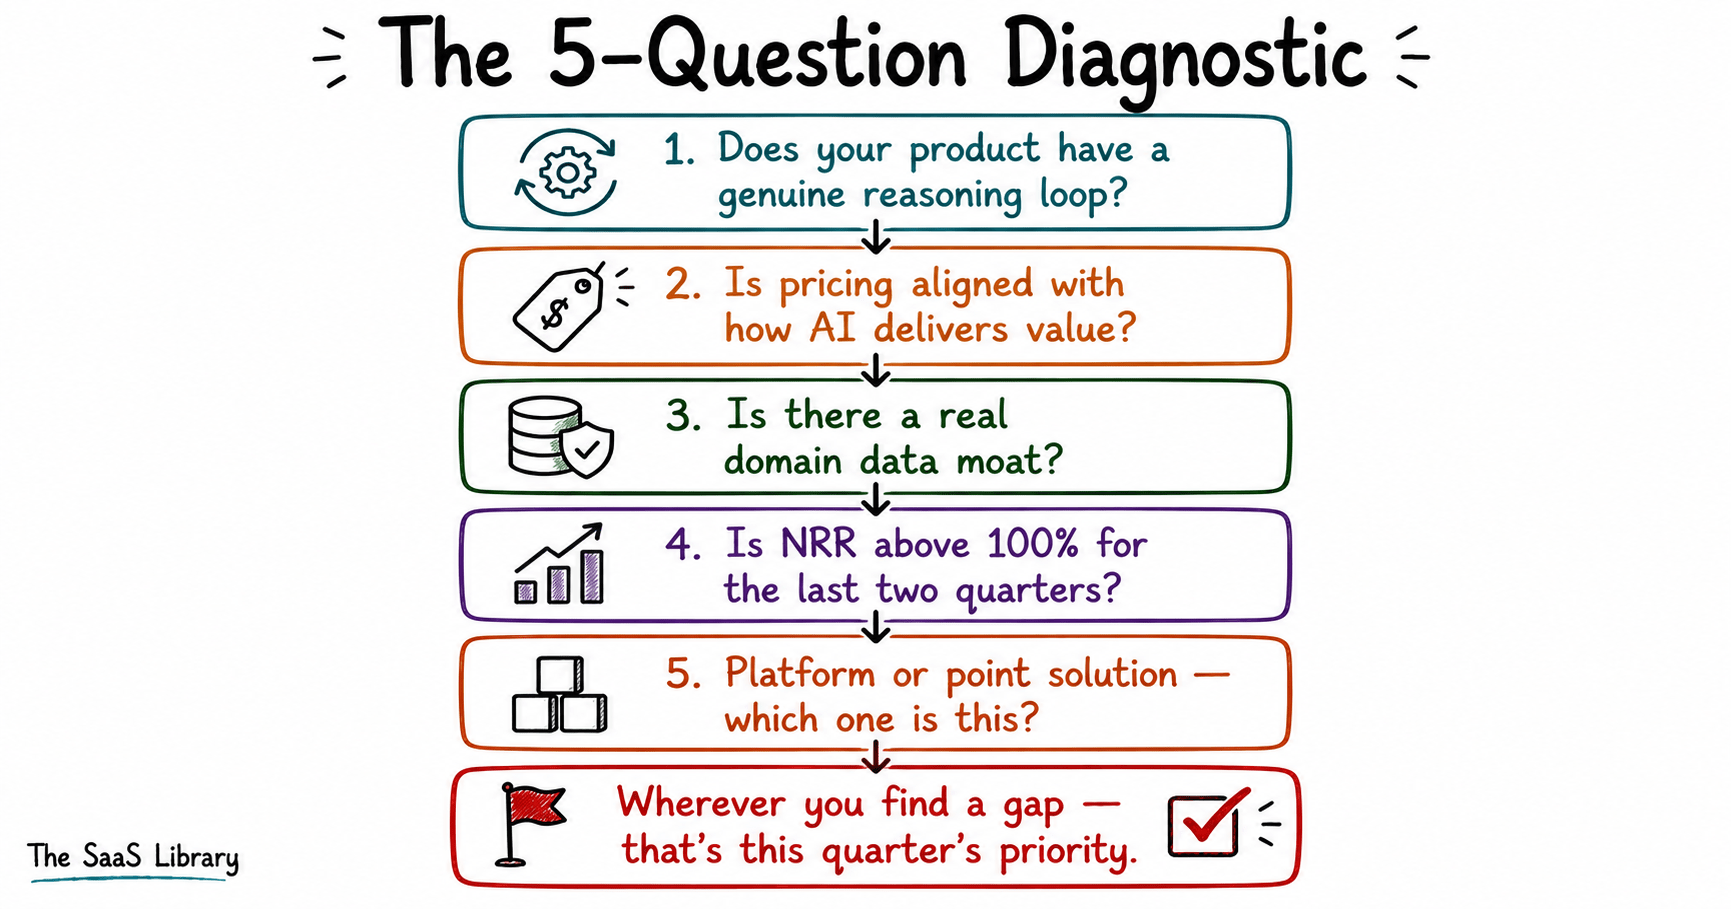
The right response to these trends is to run five diagnostic questions against your own business — AI readiness, pricing fit, vertical moat, NRR health, and consolidation risk — and act on whichever ones expose a real gap, since Seat Compression affects each company differently depending on where its revenue and product actually sit today.
Reading about five trends is not the same as knowing which ones apply to a specific business. These five questions turn the article into an audit.
Ask: can it complete a multi-step goal — where each step depends on what the last one found — without a human approving every decision? If yes: governance comes before scale. Over 40% of agentic AI projects get cancelled by 2027, per Gartner, largely from missing permissioning and audit controls, not weak models. See The Governance Readiness Gap for the compliance side of this specifically. If no: map the top three customer workflows. The first one where completion requires 2+ sequential decisions without human input is the agent roadmap priority.
Ask: does the current model bill by seat, even where AI reduces the seats a customer needs? The risk: per-seat pricing punishes success — a customer using AI to do more with fewer people pays less, exactly when the product is working best.
Ask: is there 3+ years of proprietary, industry-specific data — patient records, legal case history, transaction patterns — that a general-purpose competitor can’t access? The opportunity: vertical SaaS sold at a 41% M&A premium over horizontal SaaS in 2025 — the widest gap on record — specifically because domain-specific AI outperforms general models on the same task.
Ask: has net revenue retention held above 100% for two consecutive quarters? If below 100%: this is a product-market fit problem, not a retention-operations problem — no acquisition spend fixes a structural retention gap. If 100–110%: there’s an expansion-architecture gap — find the upgrade path the best customers take on their own, then make it the default for everyone. If above 110%: protect whatever created it — it’s already producing the valuation premium McKinsey’s 24x-vs-5x data describes.
Ask: in enterprise accounts, is the product embedded across 3+ workflows and budgeted as infrastructure, or does it handle one workflow that a competitor’s feature could replace? The risk: Gartner projects 70% of organizations will consolidate to three strategic vendors by 2027 — and point solutions are the ones cut first.
Wherever you find a gap across these five questions — that’s this quarter’s priority.
Conclusion
Seat Compression explains all five trends in this article — AI agents replacing seats, pricing moving off seats, vertical and NRR-strong companies surviving compression, and enterprises cutting the tools it made redundant. None of that means SaaS is dying. It means the seat stopped being the unit that matters. The winners are building agent-native products, pricing on outcomes, and defending NRR like the valuation metric it now is. Start with the diagnostic in this article — find your gap, then act on it before the next renewal cycle decides for you.
Frequently Asked Questions
What is Seat Compression?
Seat Compression is the mechanism where an AI agent completes work that used to require a paid human seat, shrinking the number of seats a customer needs without shrinking the value that customer gets. It is the framework connecting all five B2B SaaS trends in 2026.
What caused the 2026 B2B SaaS market selloff?
The 2026 B2B SaaS market selloff was caused by investors repricing software stocks around the belief that AI agents would shrink the seats companies pay for. Software stocks lost more than $1 trillion in six weeks after Anthropic launched Claude Cowork on January 30, 2026, with losses approaching $2 trillion by spring.
What are the 5 B2B SaaS trends in 2026?
The 5 B2B SaaS trends in 2026 are AI agents replacing features as the primary unit of software value, per-seat pricing breaking down in favor of hybrid models, vertical SaaS outgrowing horizontal SaaS, net revenue retention replacing ARR as the top valuation metric, and enterprises consolidating bloated SaaS portfolios.
How many enterprise apps will use AI agents by the end of 2026?
40% of enterprise applications will embed task-specific AI agents by the end of 2026, according to Gartner, up from less than 5% in 2025.
Why is per-seat pricing breaking down in B2B SaaS?
Per-seat pricing is breaking down because AI agents complete work that used to require a paid human seat, so customers need fewer seats without needing less value. 48% of B2B SaaS companies now run hybrid pricing as their primary model, according to ICONIQ Growth’s 2026 State of Go-to-Market report.
What is NRR and why does it matter more than ARR?
NRR (Net Revenue Retention) matters more than ARR because it measures whether existing customers are worth more or less over time, which predicts growth without new customer acquisition. McKinsey found top-NRR-quartile B2B SaaS companies trade at a median 24x EV/Revenue, compared to just 5x for the bottom quartile.
Why is vertical SaaS growing faster than horizontal SaaS?
Vertical SaaS is growing faster than horizontal SaaS because industry-specific software builds deeper data moats, higher switching costs, and stronger regulatory compliance than general-purpose tools. Vertical SaaS sold at a 41% M&A premium over horizontal SaaS in 2025 — the widest gap ever recorded.
How many SaaS applications does the average enterprise use?
The average enterprise uses 305 SaaS applications, according to Zylo’s 2026 SaaS Management Index, and still leaves 46% of purchased licenses unused — worth $19.8 million in wasted spend annually.
What is a good NRR for a B2B SaaS company?
A good NRR for a B2B SaaS company depends on customer segment: Enterprise SaaS (ACV above $100,000) should target around 118%, mid-market SaaS ($25,000–$100,000 ACV) around 108%, and SMB-focused SaaS around 97% or higher, based on a dataset of 939 B2B SaaS companies.
Is B2B SaaS dying because of AI agents?
B2B SaaS is not dying because of AI agents, but per-seat pricing and horizontal, feature-only products are under genuine structural pressure. Companies embedding agents into existing products — like Salesforce’s Agentforce, which reached $800 million in ARR — are growing, while companies adding AI as a surface-level feature face the sharpest competitive risk. The full argument is laid out in Is SaaS Dead? What the Dashboard-to-Agent Shift Actually Means.
What is outcome-based pricing?
Outcome-based pricing is a model where a company charges for a completed result rather than a seat or subscription fee. Intercom’s Fin charges $0.99 per resolved customer conversation, with no seat requirement, as the clearest live example in mainstream B2B SaaS.
Why did Salesforce acquire Intercom (Fin)?
Salesforce acquired Fin, formerly Intercom, for approximately $3.6 billion on June 15, 2026, to fold its outcome-priced AI customer service agent directly into Agentforce. The deal is widely viewed as confirmation that outcome-based AI agent pricing is moving from niche to mainstream in enterprise software.
- Peter Cohan, “SaaSpocalypse Now? AI Is Disrupting SaaS,” Forbes, Feb 6, 2026
- “The 2026 ‘SaaSpocalypse’,” FinancialContent, Mar 24, 2026
- Gartner, IT spending forecast press release, Aug 26, 2025
- ICONIQ Growth, “State of Go-to-Market 2026,” Mar 2026
- Tidemark, “2025 Vertical & SMB SaaS Benchmark Report”
- McKinsey & Company, “The net revenue retention advantage: Driving success in B2B tech,” Nov 2025
- Zylo, “2026 SaaS Management Index,” Jan 29, 2026
- McKinsey & Company, “The state of AI in 2025,” Nov 5, 2025
- Menlo Ventures, “2025: The State of Generative AI in the Enterprise,” Dec 9, 2025
- National CIO Review, “Agentforce Reaches $800 Million,” Feb 27, 2026
- Salesforce, “Wiley sees 213% ROI” (customer story)
- Bain & Company, “Will Agentic AI Disrupt SaaS?,” Technology Report 2025
- Intercom, official pricing page
- Salesforce, Fin acquisition press release, June 15, 2026
- Snowflake, Q4 FY2026 Earnings Call Transcript, Feb 25, 2026
- SaaS Mag, “Why NRR Is the Defining SaaS Metric of 2026,” Apr 20, 2026
- Benchmarkit, “2026 B2B SaaS & AI-Native Metrics Report”
- SaaSRise, “Vertical SaaS M&A and VC Report 2026”
- Mordor Intelligence, “Vertical Software Market,” Mar 13, 2026
- SaaS Capital, 2026 B2B SaaS retention survey
- ChartMogul, “The SaaS Retention Report: The AI churn wave”
This is a brilliant article. Well structured. Highly researched. Top of the line.
Amazing work!
Thank you reader!
Pingback: 7 Key Strategies for Online Market Development in 2025 – kextechin.com
Pingback: Google's AI Search Guide Calls GEO and AEO Still SEO - The SaaS Library